Written by : Knowledge Centre Team
Last published : 2026-03-05
7 minutes read
Share
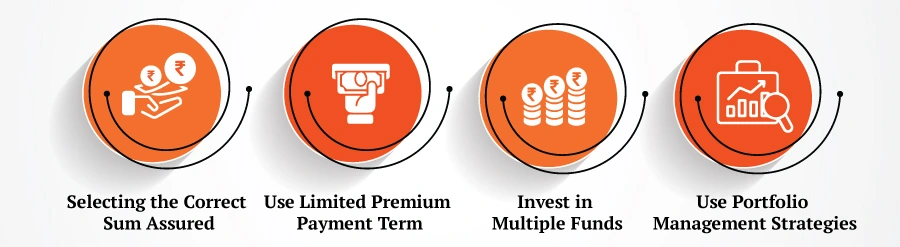
Sum assured for the life cover under ULIP plans plays an important role. The life cover increases the mortality charge on your investment. Thus, you can keep the sum assured to a minimum required amount unless you also want to use this policy as a life cover for your family or for tax saving under section 80C for the premiums.
If you have already exhausted your 80C limit with investment in other goals and plans, you are free to invest any amount in this plan. The logic behind this freedom is:
However, if there is any chance for you to withdraw the money from the plan, you should keep the sum assured to at least 10 times of the annual investment amount.
For example, if you plan to invest Rs. 2 Lakhs every year into this plan, your sum assured has to be at least Rs. 20 lakhs. The rule applies regardless of the investment tenure.
Estate transfer to the next generation through life insurance generally means – ‘transfer upon death.’ So, the policy will continue for a lifetime. However, you should not have to pay premiums after your retirement.
Limited premium payment option allows you to limit your payments into the plan until your retirement.
Even with the limited premium payment tenure, you should follow the 10% rule to avoid tax liability in case of withdrawals.
For example, whether you are planning to deposit Rs. 2 lakhs for only five years or 10 years, the sum assured should be Rs. 20 lakhs.
Based on the time available to you for the investment and your risk appetite, you can invest in a mix of equity, debt, balanced and liquid funds under the same plan.
Balanced funds are a dynamic mix of equity, debt and liquid assets. Fund managers will change the allocation according to market opportunities in these funds. However, they are usually equity heavy.
So, if you want a lower equity exposure for your investments, you can create a mix of your own.
Portfolio management strategies will help you manage the risk of your portfolio if you are investing in equity funds. These strategies will automatically adjust your portfolio so that you can benefit from market opportunities while keeping the risk in check.
For example, you can fix the ratio of debt and equity in your portfolio to 70:30. The plan will adjust your portfolio to match this ratio from time to time. This means as the markets outperform debt funds money will flow from equity funds to debt funds securing your gains. The reverse flow will happen in case markets are in a downtrend, which will boost your gains when markets rise.
The investment strategies help you accumulate your corpus in your earning years. While after your retirement you would want the accumulated money to at least not erode in value. For this, you can change your portfolio strategy to match your new goal of wealth preservation.
You can achieve this by moving your equity fund allocation gradually to a debt fund or liquid fund. Remember, however, that debt funds will be the right choice if your investment tenure is more than five years for wealth preservation.
Debt funds returns will help your corpus to stay safe from inflation, but the fund needs time to realise these returns. Liquid funds are a better choice if your remaining tenure is less than five years.
This is perhaps the easiest part, as all you need to do is change the nomination to your grandchildren in the policy. You should use an electronic insurance account (e-IA) to store and manage your life insurance policies.
e-IA will make it easier for you to change nominations and monitor your policies during your lifetime. You can also assign an ‘authorised person’ to ensure that your family can access all your active policies and file claims.
An OTP has been sent to your mobile number

Sorry ! No records Found
Thank You for submitting the response, will get back with you.
Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.
Canara HSBC Life Insurance offers online ULIP plans that blend life insurance protection with investment growth, helping you build wealth while securing your family's future.