10 ULIP Charges every planning to invest in ULIPs should know about

10 ULIP Charges You Should Know Before Investing

Understanding ULIP charges helps investors make informed decisions, manage costs better and maximise long-term returns from their investment.

Written by : Knowledge Centre Team

Last published : 2026-06-19

6 minutes read

There is no dearth of investment options in India. Investors have a variety of options ranging from term plans and unit-linked insurance plans to equity funds. Even though ULIPs are insurance products, most people consider it to be an investment product. However, many people do not take into account the impact of various charges and fees on the return from an investment product. Even a small charge over a long period can have a substantial impact on the overall returns.

10 ULIP Charges You Must Know Before Investing

Here are 10 charges every person planning to invest in ULIPs should know about:

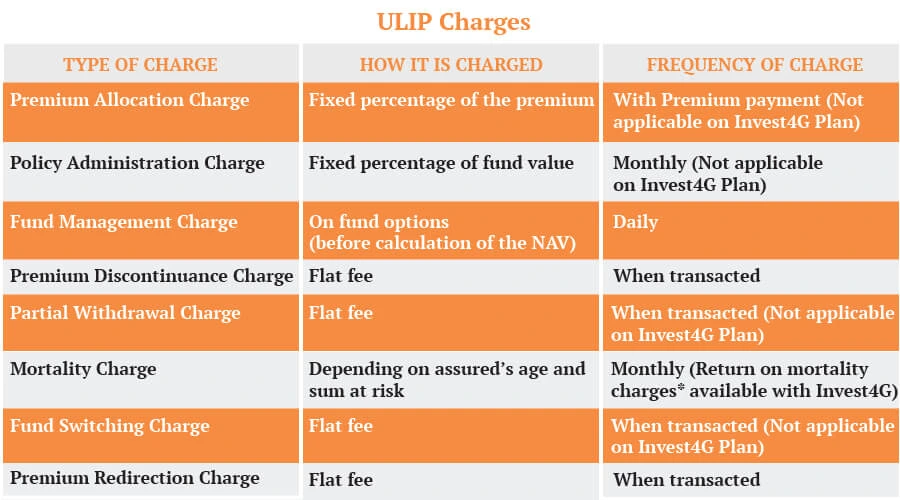
  1. Premium Allocation charge: It is one of the first charges levied on the policyholder. The insurance company deducts a fixed percentage of the premiums in the initial years to cover the cost of underwriting, medical expenses, and the intermediary's fees. The premium allocation charges are frontloaded and seem high in the initial years but taper off later. After deducting the premium allocation charge, the remaining amount is invested in an investment fund.
  2. Administration charges: The insurance company levies a certain charge every month for the administration of your policy. Unlike the premium allocation charge, administration charges are not deducted by reducing the premium, but by canceling the units from your investment funds proportionately. The best ULIP have administration charges that remain fixed throughout the policy tenure, while some have charges that change at a predefined rate.
  3. Fund Management charges: The best ULIP offer a variety of fund options to the investors, but charge a fee for the management of the funds. The fund management charges are calculated as a percentage of the fund value and deducted before computing the net asset value of the fund. As per the rules set by IRDAI, the fund management charge cannot be more than 1.5%.
  4. Discontinuance charges: As the name suggests, the discontinuance charge is levied by the insurance company if the policyholder decided to surrender the policy prematurely. The insurance regulator has mandated only the recovery of the acquisition cost in the event of discontinuance of the policy.
  5. Partial withdrawal charges: Investors are allowed to withdraw from ULIPs after remaining invested for a minimum of five years. In the event of a withdrawal, the insurance company levies a partial withdrawal charge.
  6. Mortality charges: Getting a life cover along with market-linked returns is one of the biggest benefits of ULIP. The insurer levies a mortality charge to provide the insurance cover. The mortality cover is calculated after taking into account factors such as age and health risk of the insured
  7. Switching charge: One of the benefits of ULIP is the host of investment funds that it offers ranging from debt funds to equity funds. The policyholder also has an option to switch between funds depending on his/her risk profile. Insurance companies offer a fixed number of free switches but start imposing a nominal switching charge after the exhaustion of free switches.
  8. Premium redirection charges: If you redirect future premiums into a different fund without altering the original fund structure, the insurance companies levy a premium redirection charge.
  9. Guarantee charges: The best ULIP provide market-linked returns, but some investors seek surety in the rate of return. Some insurers impose a guarantee charge and ensure a minimum rate of return for the insured.
  10. Rider charges: ULIPs essentially are insurance products. Besides providing a life cover, life insurance policies provide several riders, which are optional on the insured. Similarly, in the case of ULIPs, you can opt for riders like accidental death rider or critical illness rider. To enhance the life cover through riders, insurers levy rider charges.

Conclusion

Even after multiple charges, ULIPs are one of the best insurance-cum-investment options in the market. Some of the charges are dependent on the action of the policyholder and may not be levied. To maintain transparency, the insurance regulator has capped the annualised charges of ULIPs at 2.25%. The Invest 4G unit-linked plan offered by Canara HSBC Life Insurance can help you fulfill your financial goals with ease and at a nominal price. With the ULIP plan, you can live a stress-free life without worrying about excessive fees and charges. Lower fees automatically boost the overall returns for the investors
Recent Blogs

ULIPs for Stable Wealth Generation

Why ULIPs Are Ideal for Stable Wealth Generation?

07 Aug '26
6 minute read
Stable fund generation requires the right investment vehicle. Know why unit-linked plans are ideal for building a consistent fund corpus with market-linked growth, flexibility, and long-term wealth creation.
Read More
Ulip
Which Tax Regime Is Right For You In 2025 Thum Desktop

ULIP vs SIP: Top-Up vs New SIP & Which Is Better

06 Aug '26
7 minute read
ULIP top-up or new SIP? Compare flexibility, returns, risks, and costs to make an informed decision for wealth growth and financial planning.
Read More
Ulip
Portfolio Management Strategies in ULIPs

What are the Main Portfolio Management Strategies in ULIPs?

29 July '26
8 minute read
Learn four popular ways to manage your ULIP portfolio, including fund allocation, switching, premium redirection, and regular reviews to align with changing financial goals.
Read More
Ulip
What Is Ulip Thum Desktop

10 Wealth Creation Tips: Grow Money & Build Long-Term Wealth

29 July '26
6 minute read
Discover ten practical wealth creation tips to grow money steadily, manage risk wisely and stay focused on long-term financial goals through disciplined planning.
Read More
Ulip
Benefits of Buying the Best ULIP Online

5 Benefits of ULIP Plans: Advantages, Tax & Wealth Growth

29 July '26
8 minute read
ULIPs offer life cover & market-linked returns. Learn 5 key benefits and advantages of investing in the best ULIP online & achieve long-term goals.
Read More
Ulip
Impact Of Market Performance On Ulip Returns Thum Desktop

ULIP Returns: Market Impact & How to Maximize Growth?

29 July '26
7 minute read
Learn how market cycles affect ULIP returns and discover strategies to maximize growth and improve long-term investment performance.
Read More
Ulip
What Is ULIP

What Is ULIP Plan? Full Form, Meaning & Benefits (2026)

23 July '26
7 minute read
What is ULIP? Learn its meaning, full form, benefits & why investors choose ULIPs for tax savings and long-term wealth creation.
Read More
Ulip
How to Choose ULIP Funds

How to Choose ULIP Funds: Types, Risk Profile & Strategy

22 July '26
7 minute read
Know how to choose ULIP funds based on risk profile, fund types & investment goals for better returns.
Read More
Ulip
Is ULIP a Good Investment for Short-Term Gains?

Is ULIP a Good Investment for Short-Term Gains?

09 July '26
7 minute read
Discover whether ULIPs are suitable for short-term investment goals and understand the risks, returns and lock-in period.
Read More
Ulip

Unit Linked Insurance Plans - Top Selling Plans

Canara HSBC Life Insurance offers online ULIP plans that blend life insurance protection with investment growth, helping you build wealth while securing your family's future.

Wealth Today, Protection Always

Promise4Growth Plus
  • Life Cover up to 100 Years
  • 13 Fund Options
  • Fund Switching Option
  • Waiver Of Premium

Secure Your Future with Confidence

SecureInvest
  • Life Cover up to 100× Annual Premium
  • 12 Fund Choices
  • Automated Portfolio Strategies
  • Maturity Booster

Invest Smart, Live Smart

Wealth Edge:
  • Flexible Premium Options
  • Multiple Fund Allocations
  • Systematic Withdrawals
  • Premium Waiver Benefit