Written by : Knowledge Centre Team
Last published : 2025-09-27
8 minutes read
Share
Nowadays it is natural to be too busy with all the things at hand - Career, family, children, friends and parents, if you could manage it, perhaps you won’t even have time for yourself. But, like so many things inevitable in life, certain financial goals are inevitable yet ignored, in the hopes of a better time.
Retirement is one such financial goal, and you should not doubt that there will be a day when you would want to hang your boots and relax. If you have not started planning for your retirement, perhaps now is the time to start! Unit linked Insurance Plans offer great opportunities to capture growth and boost your wealth for a sufficient retirement bonus.
If you are in your 30s right now, retirement is an important goal for you, but it’s a long way away. Therefore, you will need your retirement plan to have the following characteristics:
Helps you build a strong retirement corpus
Works in auto mode without your regular attention
Whatever investment route you choose for investing in your retirement must fulfil both traits at the same time.
An OTP has been sent to your mobile number

Sorry ! No records Found
Thank You for submitting the response, will get back with you.
Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.
Fixed income instruments must offer market-linked returns so that your retirement corpus can keep up with the inflation. Equity investment on the other hand is highly volatile and hard to time, so unreliable for an important goal like retirement.
That means the investment route cannot be a low return fixed-income instrument or a 100% equity (high-risk) investment. The ideal retirement plan would be a mix of both and should have good tax efficiency.
This is where unit-linked insurance plans or ULIPs come into play. ULIPs offer all the qualities we are looking for in our ideal retirement plan. 100% debt portfolio may cause you to worry if the corpus will be sufficient, while 100% equity investment may give you sleepless nights during large downturns.
We have already discussed what you will need from your ideal retirement plan. ULIPs have all the features you need to create your ideal investment plan for retirement.
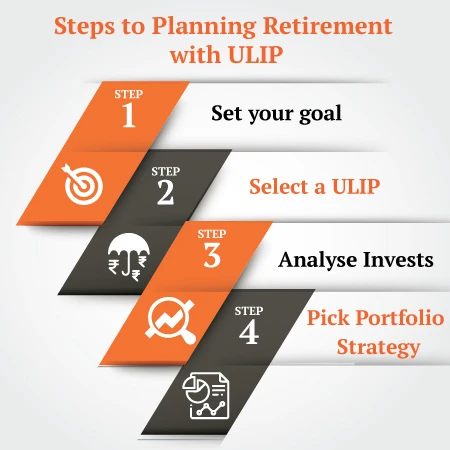
Following steps should help you create your ideal retirement plan with a ULIP:
In this step you need to define the following 3 aspects of your retirement goal:
How much time do you have to retire?
How much money would you need from this ULIP at retirement?
Where do we stand right now?
Time: Time to retirement depends on your current age, as we take the expected retirement age at 60. So, if you are 30 years old right now, you have about 30 years to achieve your retirement goal.
Amount: The second question needs a lot more calculations, but let us simplifies them for our case here. Assuming your and your spouse’s current annual expense stands at ₹6 lakhs a year. Growing at 5% average inflation rate, you will need about ₹26 lakhs a year post your retirement.
To generate such an income every year you will need approximately ₹3.25 crore at the age of 60. But this is not the goal for the ULIP alone; this is your entire retirement corpus. If you have few investments already in place for retirement, you can deduct their value at 60 from ₹3.25 crore.
For example, if you are investing ₹1 lakh a year in a PPF or NPS account, you can expect about ₹1.25 crore at the age of 60. That means you will only need about ₹2 crores from the ULIP investment.
Present Situation:
If you have already started investing in a ULIP or similar pension plan you will have the following two choices:
Make appropriate changes to the existing plan and continue.
Redirect the plans to another goal and start a new investment.
Select a plan which lets you set a portfolio management strategy and has the following portfolio strategies in place:
Systematic transfer option: For once a year investors.
Automatic fund rebalancing option: Automatically adjusts your portfolio for market opportunities and safeguards returns.
Apart from these two, the ULIP should also have the option to move the entire corpus in the final few years from high-risk funds to low-risk funds. So, your accumulated money stays safe from market volatility as you approach your goal.
Canara HSBC Life Insurance offers all these features and more. Since you are going to invest for a very long time.
The answer to this question depends on:
How much you can invest?
Maintain the tax-free status of your ULIP investment.
For the case we took as an example, you will need to invest about ₹1.8 lakhs a year for the next 30 years. That is considering a conservative rate of return of 8.5% per year.
If you can invest this much start with this amount and you can stop investing in the future once your goal amount is achieved. If your current capacity allows a lower amount of investment, you will need to increase the investment later.
Maintaining your tax-exempt status of ULIP investment is easy. All you need to do is make sure the policy sum assured or life cover is at least 10 times the annual premium. For example, in our case above, the policy has to have a life cover of at least ₹18 lakh.
This step depends a lot on how frequently you invest in the ULIP investment plan.
Here we can discuss two modes of investment:
Monthly mode.
Other than the monthly mode.
If you can invest in the monthly mode you can choose the auto rebalancing option. All you need is to decide the ratio of equity and debt allocation in your portfolio in the beginning. This ratio should be based on your risk appetite and comfort with equity market volatility.
For example, if you decide a 50:50 ratio, the portfolio will rebalance the allocation regularly to meet this standard. Thus, when equity markets are performing well, your growing funds will flow to the safety of debt and vice versa when equity faces downtrend.
In case you are investing in any other mode than monthly, you can select the systematic transfer option. Allocate your premium to debt and liquid funds in a fixed ratio. Money in the liquid fund will be systematically invested in an equity fund every month, while debt investment keeps growing steadily.
Whichever portfolio strategies you choose just make sure you can bring in the entire corpus into safe funds before maturity plan from Canara HSBC Life Insurance has the option to move all your savings from equity funds to liquid funds in the final four years of the policy.
The gradual transfer doesn’t affect your corpus and helps you safeguard your retirement funds from the market movements in the final years.
Canara HSBC Life Insurance offers online ULIP plans that blend life insurance protection with investment growth, helping you build wealth while securing your family's future.