How is Your Unit-Linked Insurance Plan (ULIP) Premium Utilised?

How Your ULIP Premium Is Utilised: Charges and Investments

ULIP premium is split between life cover, investments and charges, and how this allocation changes over the policy term.

Written by : Knowledge Centre Team

Last published : 2026-01-27

11 minutes read

ULIP is a financial product that provides your life insurance cover and also acts as an investment. It combines the benefits of both insurance and investment in a single plan. Thus, this plan helps you to protect your family’s future and gives you a chance to build your wealth so you can achieve your goals. Buying the best ULIP online is one of the wisest financial decisions as it is completely hassle-free and convenient. Also, as ULIPs are known to offer the best of both the worlds - insurance and investment - you should always understand how it works so that you can gain benefits from it.

For ULIPs, as is the case with other life insurance plans, you have to pay a premium to get the policy. The premium depends on the amount of life coverage you want. The fixed premium you have to pay is used for providing life insurance as well as an investment instrument. Where the money will be invested is totally up to you. You can choose to invest either in debt or in equity or even both, known as hybrid investment.
How is Premium Allocated in ULIPs?

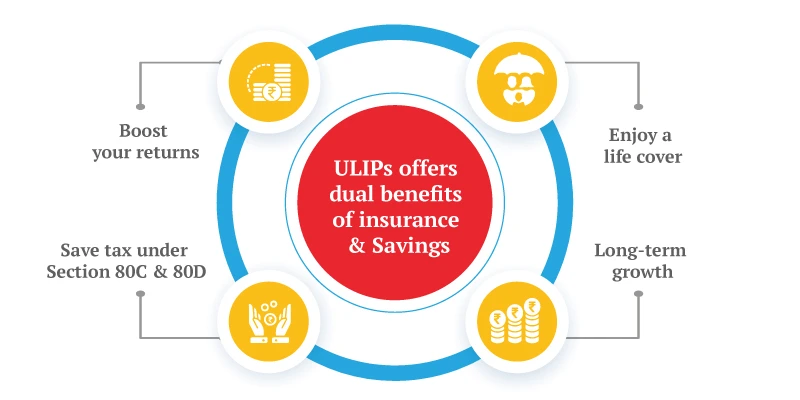
As said above the premium you pay will offer you two benefits. It will invest your amount in funds to give you return while simultaneously making sure of the fact that policyholders family stays protected. This part is done by providing live coverage.

FUNDS IN ULIPSELECTED PREMIUM ALLOCATION RATIOALLOCATION OF RS 1 LAKH P.A.ALLOCATION OF RS 20,000 P.M.
EQUITY AGGRESSIVE GROWTH FUND15%15,0003,000
EQUITY INDEX FUND15%15,0003,000
DEBT FUND GILT PLUS25%25,0005,000
DIVERSIFIED DEBT FUND20%20,0004,000
HYBRID FUND20%20,0004,000
LIQUID FUND5%5,0001,000
TOTAL100%1,00,00020,000

Table 1: Premium Allocation to various funds in ULIPs

The premium which you pay is allocated to investment. As the policies name suggests, the amount you invest is broken down into specific ‘units’.

Learn how does risk involved on ULIP investment as equity shares.

Now, the whole fund is divided into these units. You will be allocated units from these funds in proportion to the amount actually invested by you. The units value will change with a change in its underlying assets.

FUNDS IN ULIPONGOING NAV AT THE TIME OF UNIT ALLOCATIONUNIT ALLOCATION IN THE 1ST YEAR
  for the Annual Investorfor the Monthly Investor
EQUITY GROWTH AGGRESSIVE FUND25.5588.24118
EQUITY INDEX FUND150.499.7320
DEBT FUND GILT PLUS31.1803.86161
DIVERSIFIED DEBT FUND43.6458.7292
HYBRID FUND51.9385.3677
LIQUID FUND13.6367.6574
TOTAL 2,703.55540.71

Table 2: Unit allocation in the selected funds for the invested amount

If you wish to withdraw a part of your investment then the proportion of units will be sold for the payment of the withdrawal proceeds.

If due to unforeseen circumstances you die in the middle of the policy, then the death benefit will be provided to the nominee. The death benefit is higher than the guaranteed sum assured and 105% of the total premiums paid.

On the other hand, you do not die during the course of the policy, then you will be entitled to receive the total value of all the units invested by you in all the funds combined as a maturity benefit.

Charges in a ULIP

Every investment has associated expenses. The investment component of ULIP also has some charges associated with it as well. These costs are divided into several heads. The costs are deducted out of the invested premium or the fund value of the ULIP folio.

ULIPs charge the expenses under the following heads:

Premium Allocation Charge
  • Incurred by the company in allocating your premium to your market-linked securities
  • Applicable a percentage of the total premium
  • Depends upon factors such as frequency of premium, mode of payment etc.
Policy Administration Charges
  • Charges relating to the administration of the policy such as issuing dividends, managing withdrawals and nomination changes
  • These constitute in-office expenses such as paperwork
  • This can be either flat rate or can apply at a predetermined percentage
Fund Management Charges
  • Charges incurred for managing your investments in your chosen funds
  • Deducted from the fund’s Asset Value directly. NAV (Net Asset Value) estimate is after expenses
  • This is a fixed percentage. In Promise4Growth Plus, fund charges vary from 0.50-1.35% of asset value
Switching Costs
  • Charge for transferring funds from one fund option to another within the ULIP manually
  • Generally, companies provide a number of free switches
  • This is charged after that limit is exhausted
Discontinuation Charges
  • Cost for surrendering your policy before maturity or claim
  • This charge is applicable when you try to discontinue your policy within the lock-in period
Mortality Charges
  • Mortality charge is associated with the life cover provided to you during the policy
  • This amount is generally charged monthly and is levied by the way of cancellation of the existing units
  • The charge may decrease with the increase in the fund value

Premium paid by you for ULIP is automatically utilized for all of these charges, and these remain somewhat the same for all the policies.

How is ULIP Different from Other Plans?

The investment component present in ULIP is what makes ULIP stand out from the other plans on offer. The existing traditional plans include the likes of Term Insurance, Endowment plan, Money-back plan and even whole life insurance. What these plans do is provide you with a hefty life cover as well as a guaranteed maturity benefit but they do not provide investment options.

  1. Focuses on the Goals: ULIP are primarily an investment instrument, which can help you customize your savings towards a specific goal.
  2. Multiple Investment Options: ULIP will provide you with options to choose from to invest your money. It gives you full flexibility as you have full right to decide in which types of security your money will be invested. You can also invest your money in more than one fund option at the same time. While the traditional plans do not offer you this flexibility.
  3. Switching Option: ULIP gives you the ability to switch that is to change your investment fund option in the policy according to your preference.
  4. Withdrawal: ULIP allows you to withdraw funds after the lock-in period at no extra charge. Other plans charge heavy and there is a restriction as well.

Thus, ULIP provides you with ample flexibility. Policies like Canara HSBC Life Insurance P4G Plus also come with a safety switch option that allows you to switch between funds during the duration you pay your premium. The sum is invested in instruments whose returns are linked to the markets.

Get a Personalised ULIP Plan for Wealth Creation & Protection

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.
Recent Blogs

ULIPs for Stable Wealth Generation

Why ULIPs Are Ideal for Stable Wealth Generation?

07 Aug '26
6 minute read
Stable fund generation requires the right investment vehicle. Know why unit-linked plans are ideal for building a consistent fund corpus with market-linked growth, flexibility, and long-term wealth creation.
Read More
Ulip
Which Tax Regime Is Right For You In 2025 Thum Desktop

ULIP vs SIP: Top-Up vs New SIP & Which Is Better

06 Aug '26
7 minute read
ULIP top-up or new SIP? Compare flexibility, returns, risks, and costs to make an informed decision for wealth growth and financial planning.
Read More
Ulip
Portfolio Management Strategies in ULIPs

What are the Main Portfolio Management Strategies in ULIPs?

29 July '26
8 minute read
Learn four popular ways to manage your ULIP portfolio, including fund allocation, switching, premium redirection, and regular reviews to align with changing financial goals.
Read More
Ulip
What Is Ulip Thum Desktop

10 Wealth Creation Tips: Grow Money & Build Long-Term Wealth

29 July '26
6 minute read
Discover ten practical wealth creation tips to grow money steadily, manage risk wisely and stay focused on long-term financial goals through disciplined planning.
Read More
Ulip
Benefits of Buying the Best ULIP Online

5 Benefits of ULIP Plans: Advantages, Tax & Wealth Growth

29 July '26
8 minute read
ULIPs offer life cover & market-linked returns. Learn 5 key benefits and advantages of investing in the best ULIP online & achieve long-term goals.
Read More
Ulip
Impact Of Market Performance On Ulip Returns Thum Desktop

ULIP Returns: Market Impact & How to Maximize Growth?

29 July '26
7 minute read
Learn how market cycles affect ULIP returns and discover strategies to maximize growth and improve long-term investment performance.
Read More
Ulip
What Is ULIP

What Is ULIP Plan? Full Form, Meaning & Benefits (2026)

23 July '26
7 minute read
What is ULIP? Learn its meaning, full form, benefits & why investors choose ULIPs for tax savings and long-term wealth creation.
Read More
Ulip
How to Choose ULIP Funds

How to Choose ULIP Funds: Types, Risk Profile & Strategy

22 July '26
7 minute read
Know how to choose ULIP funds based on risk profile, fund types & investment goals for better returns.
Read More
Ulip
Is ULIP a Good Investment for Short-Term Gains?

Is ULIP a Good Investment for Short-Term Gains?

09 July '26
7 minute read
Discover whether ULIPs are suitable for short-term investment goals and understand the risks, returns and lock-in period.
Read More
Ulip

Unit Linked Insurance Plans - Top Selling Plans

Canara HSBC Life Insurance offers online ULIP plans that blend life insurance protection with investment growth, helping you build wealth while securing your family's future.

Wealth Today, Protection Always

Promise4Growth Plus
  • Life Cover up to 100 Years
  • 13 Fund Options
  • Fund Switching Option
  • Waiver Of Premium

Secure Your Future with Confidence

SecureInvest
  • Life Cover up to 100× Annual Premium
  • 12 Fund Choices
  • Automated Portfolio Strategies
  • Maturity Booster

Invest Smart, Live Smart

Wealth Edge:
  • Flexible Premium Options
  • Multiple Fund Allocations
  • Systematic Withdrawals
  • Premium Waiver Benefit