Life Insurance in Savings Plans

Why Life Insurance Plans Must be Part of your Savings Plan?

Discover how life insurance plans can strengthen your savings plan and secure your family’s future efficiently.

Written by : knowledge Centre Team

Last published : 2026-01-08

9 minutes read

Financial protection is a must for every individual, and relying solely on traditional savings may not safeguard your long-term financial stability. While a savings account accumulates funds, it does not account for life’s unexpected twists such as medical emergencies, sudden loss of income, or untimely death.

Being financially secure at every stage offers peace of mind and lets us focus on other important aspects of life. This is why life insurance plans must be part of your savings strategy to create a robust financial foundation for your family.

Key Takeaways

  • Life insurance enforces disciplined savings.

  • Affordable premiums with high coverage ensure protection.

  • Disability waivers maintain coverage during tough times.

  • ULIPs provide market-linked returns along with life cover.

Four Ways Insurance Plans Offer to Create a Better Savings Plan

When we think of savings, we often imagine a bank account where money quietly accumulates over time. But is that enough to secure our future? Life is full of surprises, some pleasant, others challenging. Insurance plans act as powerful partners to your savings, ensuring that your financial journey remains stable no matter what life throws at you. Here are four ways life insurance plans can enhance and strengthen your savings strategy.

  • Regular Savings: You need to pay the premiums regularly without fail at regular intervals, and you need to keep aside a certain amount each month to pay the premium. It helps you stay committed to your savings plan.
  • High Coverage and Low Premium: Life insurance plans are affordable and the coverage sum easily supplants for lost income.
  • Disability Support: If during the term of life insurance, the policyholder meets an unfortunate situation that leads to aggregate or lasting disability, the insurance supplier will pay the leftover premium payments.
  • Comfortable Retirement: Life insurance plans offer the policyholder's family adequate coverage in unfortunate events (such as the policyholder's death.) It provided financial security for the beneficiary.

Build Guaranteed Savings for Your Future Goals

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

How to Choose the Right Insurance Plan

Choosing the right life insurance plan is a crucial financial decision that depends on multiple factors. Here’s how you can decide what suits you best:

  • Define Your Life Goals: Begin by identifying your financial goals. Ask yourself:

    1. Do you need short-term liquidity, like savings for emergencies or planned expenses in the next 5-10 years?

      You can consider endowment plans, which offer guaranteed returns along with life cover and payout a lump sum on maturity.
    2. Or are you looking at long-term wealth creation for goals like your child’s higher education, marriage, or your own retirement?

      In this case, Unit Linked Insurance Plans (ULIPs) could be suitable as they provide market-linked returns with life insurance protection.
  • Assess Your Risk Appetite: Your comfort with risk plays an important role:

    1. If you prefer guaranteed returns and minimal risk, opt for traditional endowment plans that offer fixed maturity benefits.
    2. If you are open to market-linked growth with higher returns over the long term, ULIPs allow you to invest in equity, debt, or balanced funds based on your profile
  • Consider Your Stage of Life: Your age and life stage impact your insurance needs:

    1. Young professionals: Can opt for ULIPs to build wealth over time, along with life cover. Premiums are lower at a younger age.
    2. Mid-career individuals: Should focus on a mix of protection and savings plans to secure family goals while continuing wealth creation.
    3. Retirees or nearing retirement: Should prioritise plans offering guaranteed returns and stable income, like endowment plans or pension plans, rather than market-linked products.
  • Evaluate Affordability: While it is important to get adequate coverage, ensure that the premium payments are affordable. Factor in:

    1. Your existing liabilities, like loans or EMIs.
    2. Monthly household expenses and savings commitments.
    3. Future expected expenses to avoid overcommitting and impacting your financial stability.
  • Seek Professional Guidance: Finally, consult a trusted financial advisor who can analyse your income, goals, family responsibilities, and risk profile to recommend suitable plans. You can also explore Canara HSBC Life Insurance’s wide range of plans, including:

    1. Endowment Plans for guaranteed savings with insurance.
    2. ULIPs for market-linked wealth growth with life cover.
    3. Pure protection plans for high life coverage at affordable premiums.

This ensures you build a balanced and tailored financial portfolio, safeguarding your family’s future while achieving your financial dreams with confidence.

Importance of Integrating Insurance with Financial Planning

Integrating life insurance with financial planning ensures that your savings do not erode in unforeseen situations. It helps you:

  • Build a contingency plan for emergencies.

  • Create a disciplined saving habit.

  • Achieve financial goals without derailing family security.

  • Protect long-term wealth creation from medical or life risks.

Three Types of Life Insurance Cum Savings Plan
 

1. Endowment Plans:

Endowment plans are a mix of life insurance and savings. It is the best choice for policyholders who want to save regularly over a period. The policyholder receives a lump-sum amount at maturity if they survive the policy term.endowment-planning
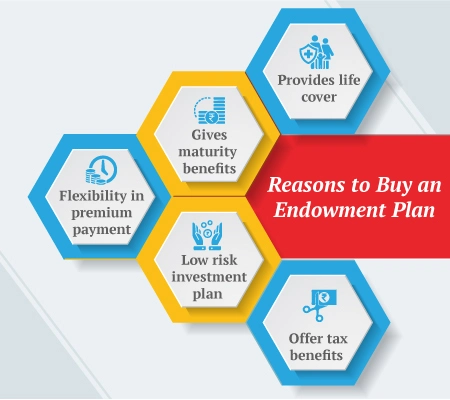
In case of any mishap during the policy term, the beneficiaries receive the entire sum assured by the policy. There are two types of endowment plans offered:

  • With-profit and participating plans: If the insurance company earns a profit in a financial year, the profit is distributed in the form of a bonus to the with-profit participating policies, eligible to earn a bonus.
  • Without profits or non-participating plans: Without profits policy, do not earn a bonus. The bonus is not added to non-participating endowment plans even if the company declares a bonus.

2. Money-back Plans:

In this plan, money-back plans are a mix of insurance and savings, just like the Endowment plans. However, the insurance company pays the sum assured at periodic intervals rather than a lump-sum amount at the end of the policy term.

The balance sum assured is paid once the insured survives the policy term. In case of a mishap, the entire sum assured is paid irrespective of the pay-outs already made during the policy term.

However, the sum assured is given at periodic intervals only if the policyholder has not missed any payment.

Learn if money back plans are beneficial.

3. Unit-linked Insurance Plans:

Life insurance plans from Canara HSBC Life Insurance allow you to modify the sum assured during the policy term.

Most of the plans are flexible and provide the option to opt between linear increasing and decreasing sum assured while simultaneously selecting a premium payment schedule. The plans also allow premium payments on a monthly, quarterly, half-yearly or annual basis.

ULIPs can help raise more money. Unit Linked Insurance Plans are of three types:

  1. Single/regular premium plans: Flexibility to choose to pay a lump-sum amount as a premium for ULIP or to invest small amounts at regular intervals. One-time premium payment plans are single premium plans, and multiple premium payment policies are known as regular premium plans.

  2. Guarantee/non-guaranteed plans: ULIPs offer guaranteed benefits to attract investors with lower risk appetites and non-guaranteed plans that do not offer assured benefits but provide various fund options according to the market conditions.

  3. Life stage-based/non-life stage-based plans: Life stage-based ULIPs modify the investment portfolio according to the life stage of the insured to ensure that the asset allocation reflects the age and risk profile of the investor.

Final Thoughts

In today’s dynamic and uncertain world, relying solely on savings is not enough to secure your financial future. Life insurance plans play a crucial role in strengthening your savings by instilling financial discipline, offering protection against life’s uncertainties, and ensuring peace of mind for you and your loved ones.

By integrating life insurance into your savings strategy, you create a robust financial foundation that safeguards your goals, protects your family’s future, and provides confidence to navigate every stage of life.

Canara HSBC Life Insurance is committed to supporting you with solutions that empower you to build a secure, stable, and worry-free financial journey.
Recent Blogs

Compound Interest Beat Inflation Thum Desktop

Why Do You Need Savings and Investment Plans in India?

07 Aug '26
6 minute read
Saving and Investment Plans help you plan your future expenses if you use your wealth. Learn why it's important, how they help achieve financial goals, build wealth, manage emergencies, and ensure long-term financial security.
Read More
Saving Plan
How To Avoid Running Out Of Money In Retirement Thum Desktop

Savings Schemes Vs Bank FDs: Which one is Better in 2026?

07 Aug '26
7 minute read
Small savings schemes or bank FDs in 2026? Compare safety, returns & tax benefits to choose the best investment option for long-term financial growth.
Read More
Saving Plan
5 Reasons To Save Money For The Future Thum Desktop

Why Is Saving Money for the Future Important?

05 Aug '26
6 minute read
Learn why saving money matters for the future, including financial security, emergency readiness, goal achievement, retirement planning, and protection against income uncertainty.
Read More
Saving Plan
10 Best Saving Plans To Consider Thum Desktop

10 Best Saving Plans to Consider in 2026

31 July '26
7 minute read
Owning a good savings investment plan is ideal because it allows you to invest and double your money in a systematic order. This not only becomes beneficial for you but also for your family as well.
Read More
Saving Plan
Senior Citizen Savings Scheme Thum Desktop

Senior Citizen Savings Scheme (SCSS): Benefits & Eligibility

30 July '26
10 minute read
Learn what the Senior Citizen Savings Scheme (SCSS) is, how it works, interest rates, eligibility rules and why it is a popular low-risk option for retirees.
Read More
Saving Plan
Monthly Income Plans Thum Desktop

Monthly Income Plan: Best Investment Options for Regular Income

30 July '26
17 minute read
Understand what Monthly Income Plans are along with their types, features and benefits. Learn how to choose the best investment plan for steady and reliable monthly income for your future.
Read More
Saving Plan
All You Need To Know About Kisan Vikas Patra Thum Desktop

Kisan Vikas Patra (KVP): Benefits, Interest Rate & Features

30 July '26
11 minute read
Explore Kisan Vikas Patra (KVP) scheme benefits, interest rates, eligibility and key features to understand how this government-backed savings scheme works.
Read More
Saving Plan
All You Need To Know About Voluntary Provident Fund Thum Desktop

All You Need to Know About Voluntary Provident Fund (VPF)

30 July '26
9 minute read
Learn what a Voluntary Provident Fund (VPF) is, how it works, its benefits, tax advantages and why it’s a smart savings tool for future security.
Read More
Saving Plan
How Is The Guaranteed Maturity Benefit Calculated Thum Desktop

How Is Guaranteed Maturity Benefit Calculated?

28 July '26
6 minute read
Life insurance policies come offer maturity benefits that makes your investment worthwhile. Know how guaranteed maturity benefits in a life insurance plan is calculated.
Read More
Saving Plan

Savings and Investment Plans from Canara HSBC Life Insurance

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan Options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover

Save, Dream, Plan. Live Peacefully

iSelect Guaranteed Future Plan
  • 4 plan options
  • Guaranteed Maturity Benefit
  • Premium Protection Cover
  • Tax Benefits