Term Insurance Calculator

Using a Term Insurance Calculator to Estimate Your Cover

A term insurance calculator estimates the right cover by assessing income, expenses, liabilities, dependents, and future financial goals.

Written by : Knowledge Centre Team

Last published : 2025-12-12

11 minutes read

Term insurance is supposed to be the ultimate financial support for your family in case of your untimely demise. Thus, the benefit amount of your term plan should match whatever you will contribute towards your family’s life.

Since this contribution is a direct result of your financial worth, the sum assured of your term plan should be equal to your financial worth. So, when we estimate our term insurance need using term insurance calculator it should give us a pretty good idea of our financial worth today, should it not?

Let’s find out…


What Your Family Will Need In Your Absence?

  • Monthly kitchen & household expenses
  • Money to meet children’s higher-education & marriage expenses
  • A corpus for the post-retirement life of your spouse

Monthly household expenses

The first thing you should account for is the monthly household expenses of the family. Term insurance should either offer the family a monthly income or enough money to generate a monthly income equal to their monthly household budget.

For example: if your current monthly household expense is Rs. 50,000 (or Rs. 600,000 a year). You’d need to add about Rs. 1 crore (max.) to your term insurance death benefit.

Now in Canara HSBC Life’s iSelect Smart360 Term Plan you can choose whether this is paid in a lump sum or as a monthly income or even both. This will help your dependents continue their lives without stressing about the income.


Money for Retirement & Children’s Goal

In our example we have already included the money for the post-retirement expenses of spouse in the monthly household expense. That is because we considered the household to run forever. However, in reality, the major part will probably stop within 20-30 years.

Thus, over time the reduced household budget would equalize the remaining corpus and work as a buffer for retirement.

Estimating the goals’ cost would be rather simple, as you can simply take the current costs of the goals.

For example, higher education in top domestic institutions may cost somewhere from Rs. 10 lakhs to 15 lakhs. Add to this a similar amount for marriage and you have about Rs. 25 – 30 Lakh more. If you have two children, simply double it to Rs. 50-60 lakh.


What Should Be Your Term Insurance Sum Assured?

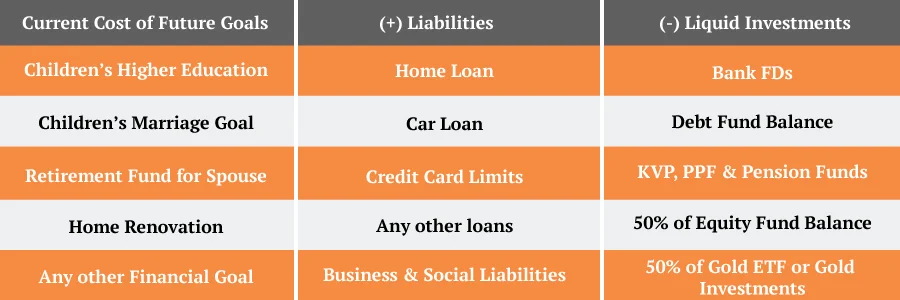
To properly estimate your term insurance need at this moment, financial planners use a method similar to the one given below:
Explaining the Typical Costs & Assets

While you can understand and agree with most of the assets and costs the following are more than they look at the surface:

  • Home Renovation Costs: If you are staying in your own house with your family, it is likely that the property will need a major rework after 10 - 15 years. Since this could be an expensive exercise, leaving the cost out of insurance can overburden your families limited resources after your untimely demise.
  • Any Other Financial Goals: You should consider any goals which are, or going to be important for your family. For example, a trip to a specific country or culture. A business venture or activity. It’s always good to keep these aspirations covered.
  • Credit Card Limits: You should consider including your credit card limits to your insurance cover. The reason is simple, in case of sudden demise, your family will need immediate financial support, and credit cards can easily fulfil that. However, every penny spent will become a liability which the claim amount can later fulfil.
  • 50% on Equity & Gold Investments: Although it’s better that you do not consider these assets while estimating your term cover benefit, you may take 50% of their value. The simple reason is their volatility, they may be looking good right now, but you never know where they may end up at the time of claim.
  • Why Not Consider Real Estate: Real estate is not considered here for two reasons:
    1. It is not easy to convert to cash
    2. It may help your dependents generate additional income

What’s your financial worth today?

Now, taking our example one step further, let’s assume the sum total of your current assets which can be easily converted to cash comes out to be Rs. 15 Lakhs.

Thus, your total life insurance need would be somewhere about…Rs. 1.5 crore (incl. 1cr. Household + 60 Lakh for Children – 15 Lakh Assets)

This is your approximate contribution to your family’s lives for all the years you stay with them. In a way, this is your approximate financial worth for your family.

Click here to use Compound Interest Calculator

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

How Does The Term Insurance Calculator Work?

The term insurance calculators work on approximation basis. The general thumb-rule in the insurance industry is,

‘10 to 20 times of annual take-home income is sufficient to look after the dependent’s expenses’

Therefore, most term insurance calculators simply ask for your current age and annual income. As in our example, the annual income of our hero could be anywhere between Rs. 12 – 15 Lakh. (That is assuming 50% of his/her monthly income goes towards household expenses)

Thus, as per an online term insurance calculator, this person’s financial worth at the moment ranges anywhere between Rs. 1.2 crore to 1.5 crores.

Now, this estimate is pretty close to the one we estimated using the detailed ‘need analysis’. So, we can say that ‘the online term insurance calculator provides a pretty good approximation of your financial worth today,’ if not the most accurate.

Choosing the Best Term Insurance Plan

Once you have calculated your financial worth, you can go ahead and look at the other features and benefits to figure out the best term insurance for your family. Few of these features we have discussed earlier, for example, regular income pay out after claim. Others that you can look for are:

  • Premium payment mode: Monthly mode is the most convenient if you are salaried. The nominal premium can be deducted automatically from your account.
  • Whole life Cover: Just in case you feel like using your term plan to ensure an estate for your children or grandchildren, a whole life term plan can make it possible.
  • Option to Increase the Cover: If you are one of the early buyers of term insurance, you may expect your responsibilities to grow as your family and responsibilities grow so should your term cover. Thus, a term plan which gives you this opportunity without having to undergo the whole underwriting process is better for you.
  • Limited Pay Option: Limited pay option can ensure that you don’t have to pay premiums after your retirement if you choose a long term cover.

So don’t compromise on your family’s financial safety. Use the term insurance calculator and estimate your financial worth to buy the adequate life cover your family will need.


Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process