Adequate Term Insurance Plans in India?

Do Women Buy Adequate Term Insurance Plans in India?

Term insurance plans for women offer affordable life cover and financial security to protect family needs and future goals.

Written by : Knowledge Centre Team

Last published : 2025-10-09

7 minutes read

Mortality Protection Gap or MPG is a data that is released by the world’s largest re-insurer, Swiss-Re every year. MPG shows the gap between the required financial protection and present life cover of the people in a country.

According to the latest data (2020), Indian people have the largest MPG of about 83%. This means if they need a term insurance plan of ₹100, they only have about ₹17 as the sum assured in their term insurance plans.

Single Income Families & Personal Priorities

With such overall statistics, when it comes to women in the country, their participation is even lower whether earning or not. Now one of the big reasons is that India is still dominated by single-income families.

Thus, the life insurance majorly concerns the male member of the family who is earning. Does this mean that women in double-income families are buying adequate term insurance?

Probably not, as the Swiss-Re study points out. Even when women are the breadwinner in the family they tend to prioritise health over life. So, either they do not feel the need to buy term insurance or get a small life cover plan.

Even after buying many discontinue the policy after a few years considering term insurance cover to be unimportant.

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Financial Value of Homemakers

There cannot be a greater myth than that the homemaker does not have financial value for the family. Although it is difficult to estimate the value, it’s not impossible.

Estimating the economic value of a homemaker without a formal income needs the replacement method of calculation.

For example, homemakers contribute to the family and children’s welfare, and in their absence all of it must be replaced. But most of these replacement services will cost money:
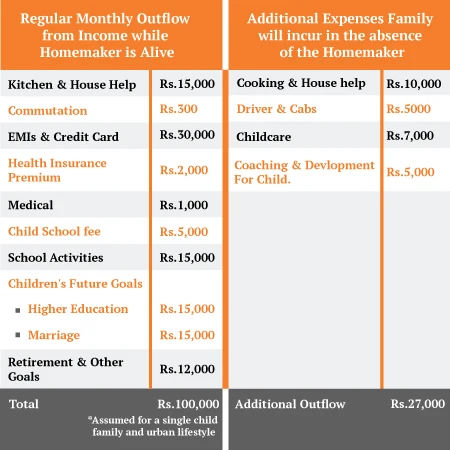
If your family’s monthly budget looks something similar to the table above, you can see the impact of the additional outflow. You will need to adjust that extra ₹27,000 within your monthly budget.

This will directly impact your investments towards your children’s and your own financial goals. Unless the homemaker also has a term insurance plan with adequate life cover.

How Much Life Cover Would You Need?

  • For Homemakers: Using the replacement method above, the family will need ₹27,000 every month to continue their lives without affecting their financial status. To generate ₹7,000 every month from a lumpsum investment in a low-risk asset the family will need about ₹51 Lakh (Estimated at 6% p.a. for a period of 50 years).
  • For Earning Women & Primary Breadwinners: If you are earning money from formal employment or business, estimating your economic value becomes easier. You can simply aim to replace your income for the family.

    For example, if you are earning ₹100,000 a month, you should buy term insurance of approximately ₹2 crores.

You may find the premium slightly high for this term insurance cover. But, in any case, you should have a life cover which is at least 10 times your annual take-home income; i.e. ₹1.2 Crore in the example above.

Is Term Insurance Sufficient?

Term insurance or life cover is important but definitely not sufficient financial protection for your family. You should always consider additional benefits or riders with the term insurance plan.

You can buy riders like personal accident and critical illness cover with your term cover and enhance your family’s financial safety.

  • Personal Accident Cover: Supports the family in case of accidental death and disabilities. PA insurance covers both temporary and permanent disabilities.
  • Critical Illness Insurance: CI cover provides financial support to you in case you are diagnosed with one of the life-threatening diseases like heart attack, cancer, renal failure etc.

Anything Else You Should Take Care Of?

You can use certain features offered by the term insurance plans, for instance the iSelect Smart360 Term Plan, to ensure a financially less stressful time for your family:

  • Regular Income Pay Out: You can choose this option and set aside a part of the sum assured to be paid as monthly income. This way your family doesn’t have to worry about investing a large sum of money to get a safe income every month.
  • Whole Life Cover: If you opt for a whole life term cover, the life cover continues till the age of 99. Meaning even natural death is covered and your children or grandchildren can receive the insurance proceeds as an estate.
  • Joint Life Cover: You and your spouse can hold a single policy which will work for both of you. This policy will work the same way as two separate policies would, but will reduce the paperwork and premiums to some extent.

Is Term Insurance Expensive?

Not really. This is the most promising feature of a term insurance cover, especially when you are younger. For example, ₹1 crore term plan will cost about ₹5500 a year if you are 30 years old female. If you choose to pay this premium every month, you will not even feel its presence (i.e. ₹500 p.m.) in your monthly budget.

Single-Premium Option

In fact, if you feel that a commitment of the next 30 years for premium is too much, you can even choose to pay the entire premium in one instance. You pay a little over ₹1 lakh for a life cover of ₹1 crore, which continues till you are 60.

Do you see any more reasons to not have adequate financial protection for your family?

Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process