Should You Surrender Term Insurance Plan When You Have No Liabilities?

Should You Surrender a Term Insurance Plan When You Have No Liabilities?

Even without liabilities, surrendering term insurance may not always be wise, as future responsibilities and dependents can still arise.

Written by : Knowledge Centre Team

Last published : 2025-11-04

7 minutes read

In a term insurance plan, the life of the policyholder is covered until a specific time. The insurance company provides death benefits to the nominee under the term insurance plan if the policyholder dies within the term period. Financial security and life cover in partial or entire disabilities, critical illnesses, and tax benefits are some common advantages that come with term life insurance.

But in the case of zero liabilities, is it wise to surrender a term insurance plan? For some, it might seem to be the most reasonable option. But it's important to measure the pros and cons of this decision.

Should you surrender the term insurance plan?

Firstly, understand what type of plan you opt for? Pure term insurance plan does not offer a policy surrendering option. In addition, if the policyholder requires no death benefit, then one can go for surrendering the policy.

Terminating the plan can also affect your family in the future, as term insurance plans provide monthly income after the demise of the sole earner.
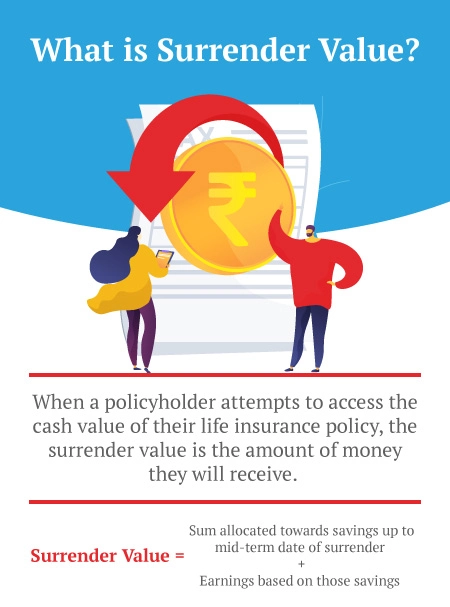
  • Surrender value: It is an amount the policyholder receives when they voluntarily withdraw from the insurance plan. The insurance company pays some amount to the insured. However, the surrender value varies according to the company's policy term.

According to India's Insurance Regulatory and Development Authority, a surrender value is fixed for the first seven years. This period is the time only after which one can surrender their term plan. Term insurance plans that include savings plans and investment plans and ULIPs are liable to surrender value. Sometimes, the surrender before maturity might also lead to a penalty.

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

4 Reasons to avoid surrendering your term insurance

A term insurance plan doesn't only bestow assurance but also several other advantages. It is usually not advisable to voluntarily surrender it. But even if you choose to do it, analyze the consequences beforehand.

  1. Effect On future premium: The Premium paid by the insured increases as he/she ages. So, if you surrender a term life insurance policy once, buying another life insurance policy will be expensive. For instance, if a person buys term insurance at the age of 25 and the life cover is one crore for 30 years, then the Premium would be ₹6,372.

    But if the previous policy is terminated and another one is bought at the age of 30 years, then the Premium would increase as much as ₹7,906. Moreover, if any medical conditions are indicated, later on, your cover might suffer.

  2. No return on Premium: Term plans such as iSelect Smart360 Term Plan by Canara HSBC Life Insurance provide an option of return on Premium after the expiry of the policy's tenure. If you surrender the plan, the policy will be terminated immediately, and you can lose this benefit.

  3. Tax benefits: The tax benefits that come along with the term insurance plans will be missed out if one decides to withdraw it before the stipulated time as per the prevailing tax laws. Thus, no tax benefits shall be available on a discontinued policy.

  4. Protection from medical ailments: Life is uncertain, and term insurance is the way to conserve your financial aspects. The policies are payable in terminal illness so that the unfortunate events don't drain you financially.

Alternatives to Surrendering Term Insurance Policy

Now that we have discussed the reasons not to surrender the term insurance, you might need to reconsider your decision. Here are some alternatives that you can go for rather than surrendering your life insurance plan.

1. Buy iSelect iSelect Smart360 Term Plan:

iSelect Smart360 Term Plan is the way to go if you want to cover all the additional benefits and secure your family's financial future. It is a highly flexible plan and caters to the insured person's needs at all walks of life. Some basic features of the policy include:

  • Add your spouse in the same plan.
  • Multiple options for limited cover periods of 5-10 years and the payment option during the working years.
  • Options to increase the life cover on different life stages and requirements.
  • The insurance includes components such as Plan Option Life, Plan Option Life with Return of Premium, and Plan Option Life Plus.

The term policies provided in this plan include the full return of the Premium you pay within the policy term when the tenure ends. It means that if any ailment or deaths occurs before the maturity period, the total Premium paid will be repaid, thus terminating the term insurance plan. In addition, an Extended Cover Period can also be added to continue the plan post-maturity.

2. Reduce the term insurance plan:

If you do not want to overburden yourself with repeated premiums, then this is a good option. In such plans, the cover amount reduces as the term maturity period comes near. It consists of lower premiums as compared to the other term policies.

Therefore, when you surrender a term life insurance policy, you lose the policy coverage. Also, the key motive of the term plans is to assist the dependants after the unforeseen death events. So, it is basically for the family's safeguarding. It is advisable to balance and think about the repercussions before surrendering your term plans.

The term insurance plans with additional benefits provided by the Canara HSBC Life Insurance come with affordable prices for life covers and benefit pay-outs to serve your needs.


Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process