Key Differences: Term Insurance Vs Endowment Plan

Key Differences: Term Insurance Vs Endowment Plan

Understand how term insurance and endowment plans work, key differences, how to choose, and how much cover you really need.

Written by : Knowledge Centre Team

Last published : 2026-01-07

6 minutes read

We live in a time where inflation affects everyone, making early financial planning essential. A good financial plan gives you clarity on goals at every stage of life and helps you invest in the right financial instruments for protection.

However, life is unpredictable. While you can’t see every twist and turn, you can prepare for them. Insurance plans are an important part of this preparation, covering goals like wealth preservation, medical emergencies, or a child’s education.

Key Takeaways

  • Starting financial planning early helps you achieve life’s big and small goals while managing inflation and unexpected events.

  • A term insurance plan gives you high life cover at a relatively low cost, ensuring your family’s income needs are protected if something happens to you.

  • An endowment plan offers the benefit of life cover along with regular savings, so you can build a guaranteed lump sum for future milestones.

  • If you cannot afford both types of plans right now, it is wise to start with term insurance for risk cover and add an endowment plan later to meet long-term financial goals.

  • Always calculate your cover carefully; term plans should ideally be at least 10 to 15 times your annual income, while endowment plans should be chosen based on specific goals like your child’s education or retirement.

Why Insurance Matters in Financial Planning

For example, to preserve wealth, you have to make sure your existing savings continue to grow. However, in case of any critical illness affecting you or your loved ones, all your savings can be drained.

You must have health insurance to ensure a medical emergency does not eat into your savings.

 Similarly, for other financial goals like a child's education, you can have an insurance policy to ensure your child meets their goal under all life circumstances.

You can have all-around protection through two plans - a term plan and an endowment plan. Let us look at the difference between the two and understand how each fits your financial planning.

The core purpose of a term insurance plan is to provide financial help to your family (nominee) in case of an unfortunate event of your demise. The sum assured in term insurance is high, and it can take care of outstanding EMIs, your child's education, and even household expenses.

An endowment plan is also a life insurance plan, but this plan comes with an additional feature:, it is also a savings plan. It helps you save regularly over a specific period and get a fixed amount on the completion of the policy.

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Difference Between Term Insurance and Endowment Plan

With different investment and financial objectives, both plans differ significantly in essential and value-added features. The most important features are compared below:

  1. Sum Assured: The sum assured in a term plan is the highest, as it is designed to provide pure risk cover. It fulfils your need for protection.

    In endowment plans, a small part of the premium goes towards the protection bucket, while a significant percentage goes to savings. Hence, the sum assured is lower in an endowment plan.

    Click here to use the Compound Interest Calculator

  2. Premium Cost: Term insurance is the least expensive life insurance product. With term insurance, you get maximum coverage while paying the lowest premium.

    An endowment plan gives you a maturity benefit along with risk cover. Participating endowment plans may also offer reversionary bonuses on maturity. The investment and growth benefits mean higher premiums.

    Though most of the premium in an endowment plan goes towards investment, only a small part covers life insurance.

    Click here to use the Term Plan Calculator

  3. Coverage Options: In general, a term insurance plan does not provide additional coverage options. However, the iSelect Smart360 Term Plan by Canara HSBC Life Insurance offers inbuilt coverages like accidental total and permanent disability benefit, child support benefit, and accidental death benefit.

    Most endowment plans provide additional coverage options like protection against critical illness and accidental death benefits.

    Also, read about Cashless Treatment

  4. Survival Benefits: As mentioned above, a term insurance plan does not have any survival benefit. This means if you outlive the policy term, you will not receive anything. However, with the return of the premium option in iSelect Smart360 Term Plan, if you outlive the policy term, you get back the total premiums paid at maturity. (Check the policy terms for any conditions that may be applied)

    As endowment plans are saving plans, they provide a fixed amount plus loyalty additions at the end of the policy tenure.

  5. Benefit Payout Options: With term insurance plans, the nominee can receive the sum assured in different ways in the event of your demise. The payout can be a lump sum, in equal instalments, or a combination of both. Depending on your needs, you can customise your payout option.

    With endowment plans, the payout is made as a lump sum, either as a maturity benefit or upon the policyholder's death.

Why Do You Need Both an Endowment Plan and a Term Plan?

An essential question for you now must be: should you choose both plans or only one of the two insurance options? You can go with both plans for different reasons. As discussed above, each serves a different purpose. You can tag them against separate financial goals and make the most of these plans.
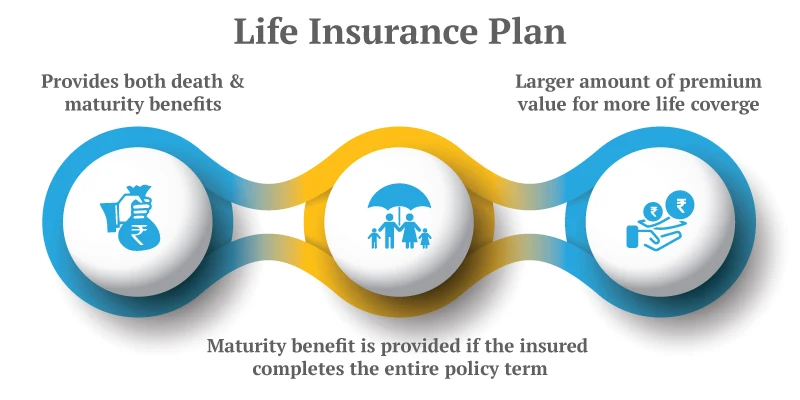
For long-term goals like a child's education or retirement, you need a lump sum amount. Also, these financial goals come with a fixed date. Hence, you should invest in secure financial instruments. Having an endowment plan for such financial goals is the right thing to do. These plans act as wealth preservation tools for you. You can live your life peacefully knowing what you will receive on maturity.

To prepare yourself for life's uncertainties and have long-term financial safety, you should also buy a term insurance plan. If something happens to you, all your financial goals will remain protected.

Also Read- Investment Plans

How Much Cover Do You Really Need?

Knowing how much cover to choose is just as important as picking the right plan. Here are some simple rules to guide you.

For term insurance: A common thumb rule is to choose a sum assured that is at least 10–15 times your annual income. This helps your family manage daily expenses, outstanding loans, and future goals in your absence.

Example:

If your annual income is ₹8 lakh, your term insurance cover should ideally be between ₹80 lakh and ₹1.2 crore.

For endowment plans: Unlike term plans, endowment plans work best when linked to a specific financial goal. Estimate how much you need for that goal and choose a policy term that matches the timeline.

For example, if you want to build a fund of ₹20 lakh for your child’s higher education in the next 10 years, you can plan an endowment policy that matures around that time.

Having the right cover amount means you stay protected while also building wealth for future milestones.

Conclusion

Having the right insurance cover is an important step towards building a secure future for you and your family. A term plan ensures your loved ones are protected against life’s uncertainties, while an endowment plan helps you build wealth for key milestones.

At Canara HSBC Life Insurance, we understand that every individual’s financial journey is unique. That’s why we offer a range of term insurance and endowment plans designed to match your goals, whether it’s safeguarding your family’s lifestyle or creating a reliable savings corpus for the years ahead.

Start planning today with Canara HSBC Life Insurance and take confident steps towards a financially secure tomorrow.


Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process