Does splitting term insurance cover a good idea?

Is Splitting Your Term Insurance Cover a Good Idea?

Learn splitting term plans into multiple policies is beneficial, how it affects cost, flexibility and claims, and when this approach makes sense.

Written by : Knowledge Centre Team

Last published : 2025-11-01

6 minutes read

Splitting means breaking down a large block into smaller parts. Having two or more policies instead of one is called splitting an insurance policy. If you are very particular about buying split policies, you may buy a normal term cover for 30 years or until retirement and buy another coverage that will cover you for life. While the first will ensure safety for the family, another will help you leave a legacy for your kids. By doing this, you are not only creating a safety net for your spouse/dependent but also creating an inheritance for your children.

Key Takeaways

  • Splitting term insurance policies often creates confusion and increases effort without offering real value.

  • A single, well-designed plan can cover loans, life goals, and legacy with better efficiency.

  • Term plans with flexible features like joint cover and return of premium add more value over time.

  • Managing one policy simplifies claims, premium tracking, and documentation for your family.

  • Choosing one robust term plan helps you save money, avoid redundancy, and build long-term security.

Do You Need to Split Your Term Insurance Cover?

It depends. Let us take an example to understand how this works so that you can weigh the pros and cons carefully before making a decision.

  • Rajesh, aged 30, is a high-flying technical leader in a cutting-edge technology start-up, earning an enviable salary, stock options, and bonuses. He owns a sprawling flat in the east of Bangalore, India’s tech hub, and pays almost a lakh in EMI each month. His kids study in a premium school, and his family lives the American dream in India.

  • As he enters the prime time of his career, the only thought that comes to his mind is, “What if I am not around?” He has witnessed several close friends or people he knows pass away (die) at an age when they should still be alive, enjoying life, spending time with family, and relaxing.

  • At 22, when he graduated from a prestigious institute in Karnataka and took up a job, he opted for a life cover of ₹ 20 lakhs with a term of 20 years. He realises, he was naive then.

  • At 30, with a family and huge debts on his head, Rajesh knows ₹20 lakhs will not be sufficient to save his flat. Keeping this in view, he is exploring buying 2 more policies worth a total of ₹.3 Crore. In case of his demise, one policy will cover the balance of the home loan, whereas the other policy can give the family some much-needed financial support. The latter has a premium-paying term of 30 years but offers protection until 85 years of age.

If your situation is similar to that of Rajesh, you may need additional cover. But it is not necessary to buy 2 additional policies unless there are clear benefits.

A term plan is a pure protection plan designed to cover home loans, which may terminate on repayment of the outstanding loan. You will need another policy to cover you even beyond that, and preferably until 99. Many people split their policies, hoping that one of the claims will get settled and their families will not suffer. This is a flawed argument because all insurance companies are regulated in India by IRDAI under the same laws.

The probability of rejection, if all records are clear, is minimal. Even in the unlikely event of a rejection, there are several levels of appellate authorities to address consumer grievances.

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Benefits and Features You Need in Your   Term Insurance Plan 

Before you jump into decision-making on either a single insurance policy or multiple insurance policies, you need to know the features and benefits of term insurance in detail. 
  • Accidental Death and/or Disability Riders: These are additional riders offered in the term plan. In the iSelectSmart360 Term plan by Canara HSBC Life Insurance, a fixed sum is immediately paid out in case of accidental death or total permanent disability. In case of total permanent disability, the life cover continues thereafter, and the future premiums are paid by the company.
  • Return of Premiums: You may not have saved a huge amount for your old age. If the insurance company returns all the paid premiums on completion of the term, you will benefit from receiving your money back.
  • Joint Life Insurance: Instead of buying two separate policies for yourself and your spouse, you must have the option to add your spouse to your policy itself. A joint policy is cheaper than buying two separate policies.
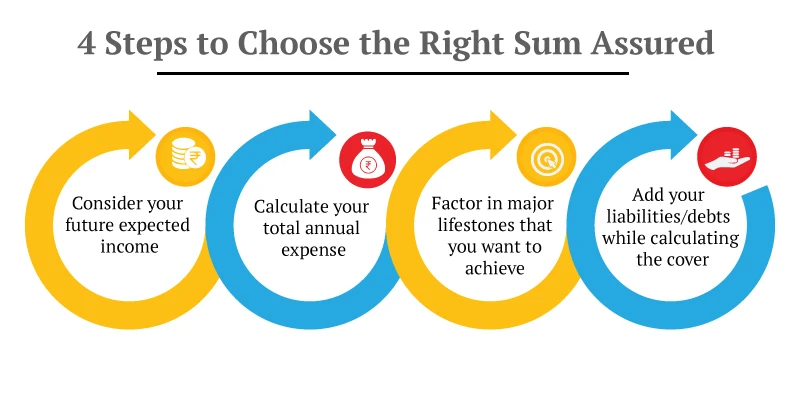
  • Increasing Sum Assured: You may begin with a smaller life cover due to limited resources. As your income grows with time and you achieve important life milestones like marriage or having children, you can gradually increase the Sum Assured. This option allows you to enhance your coverage cost-effectively compared to buying a new policy.
  • Limited Premium Pay Option: The iSelect Smart360 Term Plan by Canara HSBC Life Insurance is a flexible and comprehensive term insurance plan. It offers features like increasing life cover and the option to enhance your coverage as your needs evolve. You can also enjoy coverage up to 99 years while choosing to pay premiums only until the age of 60. This allows you to secure your family’s future and build a lasting legacy.

Disadvantages of Splitting Term Insurance Policies

The downsides of splitting term insurance are huge. These challenges can create administrative impediments and waste time. Some of the common drawbacks of splitting policies are listed below:

  • Managing Multiple Premiums: If you own more than one policy, you have created more work for yourself. Remembering dates will be the first challenge you will have, and more so if you have opted to pay at a monthly frequency. If you own, say, 4 policies that you pay for each month, you are effectively making 48 payments, each year, towards premiums for insurance policies.
  • Dealing with Different Insurers: Every insurer has its unique portal to access policy details, make payments, and download receipts. Keeping a tab on these processes, remembering the login credentials, will add to your already long list of website credentials.
  • Complicated Claims Process: In the unfortunate event of your demise, your spouse/nominee will have to file claim applications with multiple insurers and follow up until claims are settled. This can be stressful if the spouse has young kids or if the spouse is old and ailing as well.
  • Multiple Medical Tests and Documentation: Signing up for multiple insurance policies can be exhausting if all insurers trigger the need for medical check-ups. Besides undergoing similar medical tests multiple times, you will have to finish the documentation process for each of these policies separately.
  • Loss of Discounts: Insurers may offer discounts on premiums for opting for the max possible Sum Assured. Splitting policies will cause a loss of this possible discount.

Conclusion

Don’t complicate your life with multiple term insurance policies. Stick to one smart, flexible plan that grows with your needs. A single well-chosen policy saves money, reduces paperwork, and gives your family reliable support. Protect your future with confidence and deserve peace of mind that’s simple, strong, and built to last.


Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process