10-year-level-term-insurance-plan

10-Year Level Term Insurance Plan: How It Works?

A 10-year level term insurance plan offers fixed premiums and life cover for a set period, suitable for short-term financial protection needs.

Written by : Knowledge Centre Team

Last published : 2025-11-11

8 minutes read

Term insurance plan is pure life insurance offered over a specific tenure of 5 years to 20 years or more. Term insurance provides financial protection to the insured and pays a lump sum amount to the beneficiary in case of demise during the policy tenure. For example, a 25-year-old person can avail of a 20-year term insurance cover of Rs. 1 Crore for a nominal premium in the range of Rs. 500-900 per month.

The importance of buying a term insurance plan can no longer be undermined amidst the fast pace of life and rising uncertainties. Term insurance also helps the family in paying off the debts, if any, in case of the death of the sole income earner.

What is a Level Term Insurance Plan?

Level term insurance is a type of life insurance that covers you for a defined term such as 5 years, 10 years, 15 years, 20 years etc. Level term life insurance policies offer affordable insurance covers and guaranteed premiums/sum assured from the beginning until the end. The policy has a “level death benefit” for the entire tenure, implying your loved ones will receive the same sum assured irrespective of whether you die in the 3rd year or 10th year of the policy term.

Term life insurance policies expire at the end of the tenure and do not have an investment component. This means you will not receive any returns at the end of the policy period. Also, the insurance coverage ceases to exist after the end of the policy term.

Term insurance policies are extremely popular because:
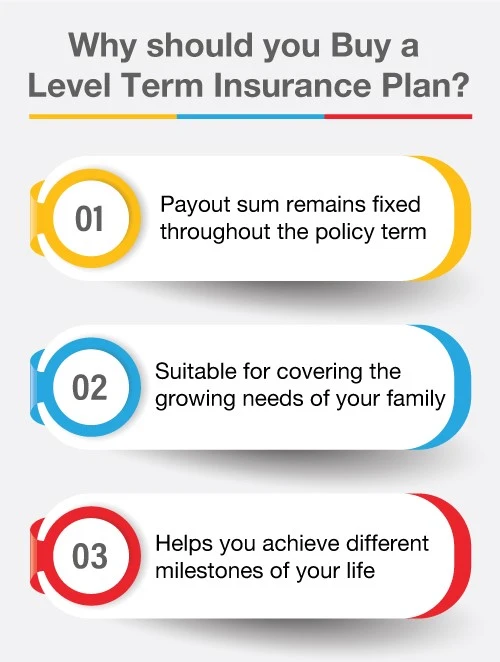
  1. They are affordable.
  2. Dependents get financially secure.
  3. Term or tenure is long enough to cover the period when one would be working.
  4. The pay-out can be used to meet lifestyle expenses, and financial obligations and/or create an inheritance.

Protect Your Family with Affordable Term Insurance

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

What is a 10-year Level Term Insurance Plan?

A 10-year term life insurance policy has the same premium and a specific death benefit for a period of 10-years. if the premiums are paid on time, your coverage will continue to exist. This coverage gives you peace of mind that your family/beneficiaries are financially safeguarded even in case of your untimely, unfortunate demise.

On reaching the end of the policy term, the policy ends albeit some policies can be renewed with the premium applicable then. You may also consider purchasing a new policy.

For example, Ramesh was recently married and is planning to start a family. He is aware of life insurance albeit he is not comfortable with the thought of paying premiums for the whole life.

Ramesh’s advisor recommends that he buy the affordable 10-year term policy now and then upgrade to a whole life policy before the end of the term. By exercising this option, Ramesh need not undergo several listed procedures again and may even be eligible for a discount on premiums.

Benefits of Buying a 10-Year Level Term Insurance Plan

As premiums on term life insurance are calculated basis age, you may want to opt for the longest possible duration to lock in a premium right now.

However, there are reasons why a shorter term may be more useful:

  1. Light on Pocket: Term policies are more affordable even with a higher sum assured because they offer protection for a shorter period.

  2. Level Premium: Once the premiums are locked against the planned sum assured, there are no changes to the policy. There will no hike in premium once the policy is issued and as long as it is in force.

  3. Planning & Budgeting:  As the premium amount is fixed, you can budget your expenses more efficiently.

  4. Income Source: With a 10-year level term life policy, you will be able to create a financial backup for your loved ones in case of your demise.

  5. Extra Protection: You can add riders to your policy to avail additional protection against accidental death, disability, and critical illnesses.

When should you Buy a 10-Year Level Term Insurance Plan?

10-year level term insurance has many beneficial scenarios. Some of these are given below:

  • Age: If you are 50+ and have a policy that matured recently, you may not be eligible to avail of a very long-term policy. A ten-year term plan can be useful to bridge the gap between the maturity of your previous policy and the upper limit specified by the insurer.

    For example, Kavitha is 58 years old and the only source of support for her husband and grandson. Due to her relatively good health, she selects a 10-year term life policy to provide financial support should she die.
  • Short Term Financial Needs: Your circumstances may make a 10-year term policy more sensible over a specific, shorter period.

    For example, Rohan is 47 years old, divorced and has a 12-year-old son for whom he wants to cover the cost of university education. He has no outstanding loans. A 10-year policy would provide a sum assured to help cover his son’s education should he die during this important time.
  • Change in Life Circumstances: The sum assured, in life insurance, is a replacement for lost income should the income-earner pass away. However, it can also provide other financial support should there be a change in your life circumstances.

    For example, Maria, a 35-year-old career woman, leaves her high-flying corporate career to care for her infant for some time. This means she will no longer have an income but plans to get back to work once her child is about 8 years old. She applies for a 10-year term policy. Should she die during this period, her family can still sustain herself with the help of the sum assured. Once she restarts work, she can apply for another term or whole life policy.
  • Smoker: If you are young and healthy but you smoke, you may still be eligible for term insurance. However, the premiums may be higher than usual. You may want a short-term policy so that you can use this tenure to quit smoking and then go for a long-term policy at lower premiums.

    For example, Janardhan is a 20-year-old smoker who plans to quit by the time he turns 27 – after he gets engaged. Janardhan chooses a 10-year term life policy. Even though the premiums are higher than normal, he will get more affordable options once he is tobacco-free.

Any sum assured should be sufficient to cover the basic lifestyle expenses of your family even when you are not around. A simple thumb rule to decide on the sum assured is to keep it at 10 times your current annual income. You must also check whether the related premium is within your budget. Having a secured financial planning for your family is important but you must keep a check on affordability and budget as well.

A 10-year term life insurance policy is suited for someone looking at short-term financial protection for their family. If you have financial obligations in the next 10-years, a 10-year term plan is best-suited to mitigate any possible risks. Such risk protection will ensure that your family can sustain expenses even in case you are not around.


Recent Blogs

Term Insurance for Diabetics in India

Term Insurance for Diabetics in India: Eligibility & Benefits

07 Aug '26
6 minute read
Yes, diabetics can get term insurance! Explore the best term plans for diabetes with Canara HSBC Life Insurance. Read more to learn about eligibility and benefits.
Read More
Term Insurance
Legacy Planning for Future Generations Matters Now

Why Legacy Planning for Future Generations Matters Now?

06 Aug '26
6 minute read
Want to secure your family's future for generations? Find out why legacy planning matters & how a term plan helps you build a lasting financial legacy.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

10 Key Benefits of Term Life Insurance You Must Know

05 Aug '26
5 minute read
Looking for the right life cover? Find out 10 powerful ways term life insurance can benefit you & help secure your family's financial future in India.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Does Critical Illness Insurance in India Cover Heart Attacks?

05 Aug '26
10 minute read
Know if critical illness insurance covers heart attacks, key conditions, payout process, waiting periods, and how it helps manage treatment costs and financial impact.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Critical Illness with Return of Premium in One Term Plan

05 Aug '26
7 minute read
Explore term insurance with critical illness cover, including return of premium, payout details and key advantages that safeguard your health and financial future.
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Why Should You Buy a Term Life Insurance Policy in India?

05 Aug '26
5 minute read
Term insurance protects your loved ones at an affordable price. Learn why term life insurance is essential, how it protects family income, covers liabilities, offers financial security, and supports long-term financial planning.
Read More
Term Insurance
Can You Increase Or Decrease Your Term Insurance Coverage Thum Desktop

Adjust Term Insurance Coverage - When & How to Update Your Policy?

05 Aug '26
5 minute read
Learn when and how to adjust term insurance coverage as life changes. Discover tips to update sum assured, riders and protect your family’s future
Read More
Term Insurance
Spouse Term Insurance Thum Desktop

Disability vs Critical Illness Insurance: Key Differences

31 July '26
8 minute read
Explore terminal illness vs critical illness and disability insurance to understand key differences, coverage features, benefits and when each type applies.
Read More
Term Insurance
Single Premium Term Insurance

Single Premium Term Insurance - Understand the Benefits

22 July '26
6 minute read
Single premium term insurance plans have been gaining popularity. Here is everything you need to know about single premium term insurance.
Read More
Term Insurance

Term Insurance - Top Selling Plans

Canara HSBC Life Insurance offers online term insurance plans to secure your family financially in your absence.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Family Shield: Enhanced Protection

Saral Jeevan Bima
  • Affordable prices
  • Multiple premium payment option
  • Get Tax benefits
  • Hassle-free purchase process