What to Know About Life Insurance Policy for Diabetics

What to Know About Life Insurance Policy for Diabetics?

Understand life insurance options for diabetics including eligibility criteria,
premium impact and approval factors.

Written by : Knowledge Centre Team

Last published : 2026-01-24

6 minutes read

Life cover assists one to face the future uncertainties, particularly with regard to the financial safety of the family. Virtually, anyone with normal and frequent income is eligible to receive life insurance cover, and so are you, despite the diabetes.

It is necessary to realise that provided you have a reasonable income and you are not at the critical phase of an illness commonly, you will be able to take out a life cover. Although such conditions as diabetes can bring a somewhat bigger premium than the individual with no underlying health conditions, it is worth it.

Finally, considering the cost-to-benefit ratio, life insurance will guarantee that your family is well off and does not experience the distress of not having you, even when your health condition changes in the future.

Key Takeaways


  •  A person with diabetes can get life insurance, but premiums are generally higher due to increased health risks.
  •  Well-managed diabetes with controlled HbA1c levels (preferably below 7.5) improves chances of approval.
  •  Age at diagnosis plays a crucial role; later diagnosis often results in lower premiums.
  •  Type 2 diabetes is viewed more favourably by insurers compared to Type 1.
  •  Frequent doctor visits indicate active management but may also raise concerns about complications.
  •  Honest health disclosure and early purchase can ensure better coverage and peace of mind.

How to Buy a Life Insurance Plan Under Diabetic Conditions?

If you are diagnosed with diabetes, you are still eligible for life insurance. However, the plan you can get and the premium you need to pay will depend on the level of your diabetes. It will always be higher compared to a person who does not have any existing medical risks.

The insurance company evaluates each case based on several factors, like:

  • Age.

  • Type of ailment (diabetes or other).

  • Stage of the illness (progressive or manageable).

  • Family health history.

In the case of applying as a diabetic proposer, you are likely to receive a higher premium quote than normal. Only on rare occasions, the insurer may reject your application altogether, such as:

  • When the risk of early demise is either very high.

  • The financial cover and cost do not resonate well.
Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Five Factors Affecting Life Insurance Choices if You are Diabetic

Getting life insurance as a diabetic is possible, but several factors influence your eligibility and premiums. Here are five key aspects insurers consider:

  • Diabetes Management/Progression: If you are diabetic but keeping it under control, getting life insurance cover could be easier for you. If you have kept a check but have additional health risks, you may or may not get life insurance. If your diabetes is not under control and progressing with time, again, you may or may not get life insurance. If you get life insurance with the last two conditions, the premium will be on the higher side.
  • Your Age at the Time of Application & Diagnosis: Age plays a critical role. If diagnosed after age 40, the impact on your insurance premium is lower compared to early diagnosis. This is because earlier onset of diabetes has more years to cause health complications.

    1. Diagnosed after 40 years: Lower risk assessment.
    2. Diagnosed before 40 years: Higher risk due to longer exposure.
  • Type of Diabetes: The kind of diabetes you have plays a major role in determining your life insurance premium.

    1. Type 1 Diabetes: Usually diagnosed early in life, requiring insulin management lifelong, leading to higher premiums.
    2. Type 2 Diabetes: Common in adults, can be managed with oral medication and lifestyle changes, leading to relatively lower premiums.
       
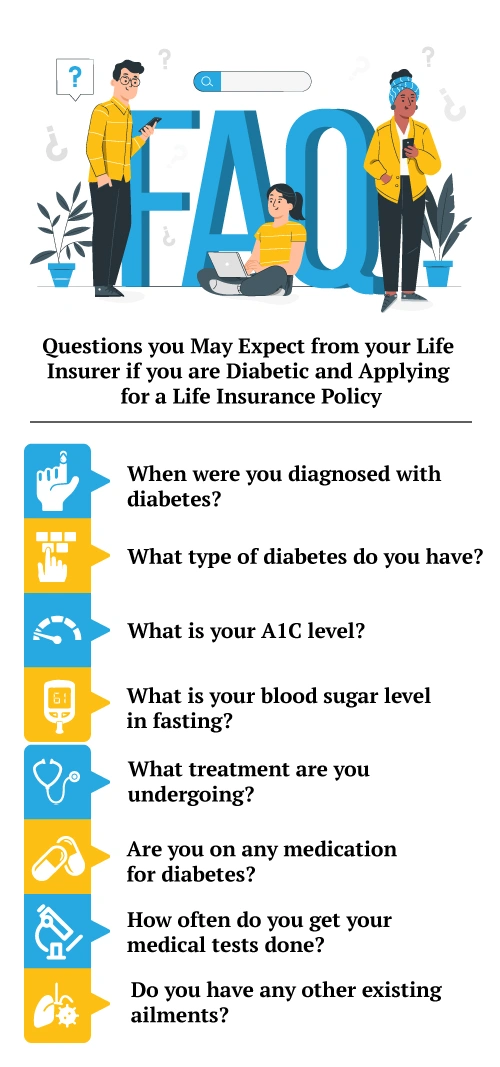
  • Your Blood Sugar Level: The HbA1c test determines your average blood glucose over 2-3 months.

    1. HbA1c ≤ 7.5: Indicates controlled diabetes, favourable for insurance.
    2. HbA1c between 7.5 – 8.5: May still be eligible with a higher premium.
    3. Fasting blood sugar ≤ 140 mg/dL: Ideal for insurance.
    4. Fasting blood sugar up to 180 mg/dL: May still be considered.

      Maintaining these levels through consistent lifestyle habits and medication is crucial for securing life insurance.
  • Number Of Doctor Visits Required: The insurance company would also be interested to know how often you visit the doctor to keep diabetes under control. If you visit your doctor twice a year, the premium will go in your favour. However, if you have to visit four or more times (once in a quarter), it tells the insurance company you are actively involved in keeping diabetes under check and may not work in your favour.

Why Does Life Insurance Premium Become an Issue of Diabetes?

The computation of the price of life insurance is against mortality risk. Diabetes:

  • Raises the likelihood of heart diseases.

  • Increases the chances of kidney failure, nerve damage or stroke.

  • Causes less lifetime expectancy when not dealt with.

Therefore, insurers take advantage of these risks by charging higher premiums. Nevertheless, this may have a drastic effect on your premium; however, early diagnosis, effective treatment, and a change in lifestyle can help significantly.

Importance of Life Insurance for Diabetics

If you are diabetic, life insurance becomes even more crucial because:

  • It secures your family’s financial future if health complications arise.

  • Provides funds to cover liabilities like home loans, child education, or spouse’s retirement corpus.

  • Offers peace of mind knowing your family will not struggle financially in your absence.

Remember, the earlier you buy life insurance, the better your premium rates, even with diabetes.

Tips to Buy Life Insurance with Diabetes

Here are summarised tips for you to remember when buying life insurance with diabetes.

  • Maintain a healthy lifestyle: Control sugar levels through diet and exercise.

  • Keep medical reports updated: Share your latest HbA1c and sugar test reports.

  • Disclose all health conditions honestly: Concealing health issues can lead to claim rejection.

  • Apply early: Premiums are lower when you’re younger and healthier.

  • Compare plans: Understand features, exclusions, and riders before purchasing.

  • Consult your insurer’s advisor: Seek guidance for the best plans suited to your health profile.

Conclusion: Diabetes & Your Health

Having diabetes shouldn't stand in the way of securing your family’s financial future. With timely medical care, proper blood sugar control, and consistent health management, getting life insurance is not only possible; it’s essential. While premiums may be slightly higher, the peace of mind and protection it offers far outweigh the cost.

Canara HSBC Life Insurance appreciates all these needs, which is why the company provides solutions that will enable you to plan with confidence regardless of your health condition. Become financially secure tomorrow by beginning today to build financial security for your family.


Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover



