


What are Maturity Benefits?

What are Maturity Benefits in Life Insurance?

Understand maturity benefits in life insurance, payout options, tax rules, eligible plans, and how maturity amounts support long‑term financial goals

Daina Mathew - Canara HSBC Life Insurance

Written by : Daina Mathew

Shraddha Tripathi - Canara HSBC Life Insurance

Reviewed by : Shraddha Tripathi

Shraddha Tripathi - Canara HSBC Life Insurance

Shraddha Tripathi

Digital Partnership
With 5 years of experience in the insurance industry, she brings a nuanced understanding of its complexities to her writing. Her expertise allows her to craft clear, insightful content that makes intricate insurance topics accessible and engaging.

Last published : 2025-12-25

10 minutes read

Maturity benefit is the amount you receive after your insurance policy reaches its term. And in some cases, the maturity amount is tax-exempt. So, it can be said that the amount a policyholder finalises while signing up for the policy in terms of 'Sum Assured' is a maturity benefit. However, the benefit may sometimes include other additions depending on the type of policy.

In simple terms, maturity benefit in life insurance refers to the life insurance maturity payout a policyholder receives once the insurance term is completed. 

Let us understand more about it in detail.

Key Takeaways

  • Maturity benefits are the lump sum amount paid by the insurance company to the policyholder at the maturity of a life insurance policy. It consists of the premiums paid and any bonus or interest earned.
  • Conventional term insurance policies do not provide maturity benefits, but certain "Return of Premium" term policies refund the premiums if the policyholder outlives the term.
  • Guaranteed income/savings plans and Unit-Linked Insurance Plans (ULIPs) offer maturity benefits, which integrate protection and savings or investment returns.
  • For maturity benefit claims, policyholders need to provide basic documents like the original policy document, proof of ID, bank details, and a duly filled-out claim form.
  • Maturity benefits are eligible for tax exemption under Section 10(10D) of the Income Tax Act as long as some conditions are fulfilled.

What is the Maturity Benefit in Insurance?

Maturity benefit in insurance is the amount paid by the insurer to the policyholder when the policy term ends and the insured survives.

When a policy attains maturity, the insurance company pays a lump sum as the maturity benefit. If your insurance policy has a 20-year term, you will receive a payout at the end of the 20th year. The maturity amount comprises the premiums paid up to that point plus any additional benefits. therefore, you should pay all the premiums to be eligible for the maturity benefit.

Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

What is Maturity Benefit in Term Insurance?

Term insurance, provides only protection and delivers no maturity advantages. For a predefined period of time, you must pay a set premium. If a catastrophic incident happens within the designated policy period (term of the policy), your nominee will be compensated following the terms of your plan.

This explains why maturity benefit in term insurance is generally not available, except under return‑of‑premium variants.

Term insurance plans do not provide maturity benefits since they do not have savings components. The explanation is that the way term plans are structured, you have to pay fewer bifurcations of premiums.

Typically, life insurance companies split your premiums into two parts:

  • One pays the expense of supplying the life insurance sum

  • The second is related to wealth creation (savings portion)

However, with term insurance, the second component is not present. The insurer uses every penny you pay, excluding a few small administrative fees, to safeguard your financial future. For this reason, maturity benefits are not offered by term plans. Nevertheless, compared to other life insurance policies, the premiums for term plans are reasonable given the greater life cover they offer.

Do you know

Did You Know?

If a policyholder dies after the policy matures but before claim settlement, the maturity benefit is paid to the lawful heirs.


Source:
Economic Times

Introducing Promise4Wealth

Life Insurance Plans with Maturity Benefits

There are different types of life insurance policies, and not all of the policies offer maturity benefits. While choosing a life insurance policy, you must evaluate your financial needs and find a plan that suits you the best.

Life insurance plans with maturity benefits combine features of life insurance with savings or investment returns, offering both protection and maturity benefits.

Listed below are a few life insurance policies that offer maturity benefits:

  • Term Insurance Plan with Return of Premium: Term plans do not offer a maturity benefit as these are pure protection plans. It offers death benefits only. However, some term plans offer the premiums back to you if you survive the policy term. Learn more about the Term plan with ROP.
  • Guaranteed Income/Savings Plan: A savings plan like the iSelect Guaranteed Future Plus by Canara HSBC Life Insurance offers life cover with guaranteed returns at maturity. 
    For example, you pay ₹20,000 per month for 10 years. You will get covered for 20 years and at the end of the 20th year, get ₹66.93 Lakhs.
  • Such plans also act as a corpus builder for your retirement. It guarantees the maturity benefit, which you can use to fulfil your life goals.
  • Unit Linked Insurance Plans: These are market-linked insurance plans in which a part of the premiums is put towards paying for the life cover, and the remainder is invested in market-linked investment choices that yield returns. A maturity benefit is given under ULIPs if you survive the policy term.

Life insurance policies are financial instruments that provide protection and an option to protect your future with the maturity benefits. Choose a policy depending on your financial goals to help you fulfill your dreams.

Calculation and Taxation of Maturity Benefits

The amount that the insurance company pays out when the policy term finishes and the policyholder survives is known as the maturity benefit of a life insurance policy. Usually, this total consists of the guaranteed amount plus any earned bonuses and any final bonuses. The calculation and taxation of maturity benefits depend on the type of investment or insurance product. Read along to find out more about maturity benefits calculation and taxation.

Steps to Claim Maturity Benefits

Claiming your maturity benefit is a straightforward process if you follow the necessary steps carefully. Maturity benefits are paid out when your life insurance plan reaches its predefined term. To ensure a smooth and timely payout, here are the steps you need to follow:

  • Required Documents: Before initiating the claim process, gather all the necessary documents. This will save time and ensure your request is processed without delays. Typically, insurers require the following documents:

    1. Original Policy Document: This serves as proof of your policy contract and is mandatory for claim processing.
    2. Duly Filled Claim Form: This form is provided by the insurer and must be completed with accurate details.
    3. Identity Proof: Aadhaar card, PAN card, or passport to verify your identity.
    4. Bank Details: A cancelled cheque or bank statement to ensure direct credit of the maturity benefit.
    5. Address Proof: Utility bill, passport, or driving licence to confirm your current address.
    6. PAN Card: This is essential for tax purposes, especially if your maturity benefit exceeds the tax-free limit under Section 10(10D) of the Income Tax Act.
       
  • Claim Process Simplified: Once you have the required documents, follow these steps to claim your maturity benefit:

    1. Contact Your Insurer: Inform your insurance provider about the upcoming maturity date. Some insurers may proactively send reminders, but it’s best to stay prepared.
    2. Submit Required Documents: Visit your insurer's branch or submit documents online, depending on the process offered by your insurance provider.
    3. Document Verification: The insurer will verify the submitted documents to ensure all details match the policy records. This step is crucial for claim approval.
    4. Approval and Payout: Once verified, the insurer will approve the claim and initiate the payout. The maturity benefit amount will be transferred directly to your registered bank account.
    5. Follow-up: In case of delays or if additional documents are requested, follow up with the insurer's customer service team for timely resolution.

Claim settlement timelines and documentation requirements are governed by insurer guidelines and regulatory norms.

Wrapping Up 

Maturity benefits in insurance refer to the lump-sum payment an insurance company makes to the policyholder when their insurance policy reaches its term or maturity date. This payout typically includes the premiums paid over the policy term, along with any applicable bonuses or interest accrued.

Obtaining maturity benefits is easy, typically involving the submission of a policy release form and required documentation to the insurance provider. Policyholders should carefully review the terms and conditions of their policy to understand the maturity benefit details and ensure a smooth claim process. Maturity benefits can be a significant financial milestone, making life insurance an essential component of comprehensive financial planning.

Glossary:

  1. Accrued Interest: Interest that has accrued but not yet been paid on a loan or other financial obligation is referred to as accrued interest.
  2. Lawful heir: A person or group of people legally entitled to inherit the assets and property of a deceased person
  3. Policy Maturity: The stage when a life insurance policy completes its term and becomes eligible for a maturity payout
  4. Guaranteed Maturity Benefit: A fixed amount promised by the insurer to be paid to the policyholder at policy maturity.
  5. Life Insurance Maturity Payout: The lump sum amount paid by the insurer to the policyholder when the life insurance policy matures
Glossary book
Uncertain About Insurance

This depends on the type of policy and the insurance company. Rather than a single lump sum payment, some plans enable periodical maturity distributions depending on installments. Before moving forward, it is best to clarify this with your insurance company and/or agent.

Section 10(10D) of The Income Tax Act, 1961 allows policies to be selected for tax-free maturity advantages.

TDS at the rate of 5% shall only be deducted if the payer's income portion of the life insurance policy payment is above ₹1 lakh in a fiscal year. If the maturity amount is more than ₹1 lakh, 5% TDS is subtracted before the maturity proceeds are paid.

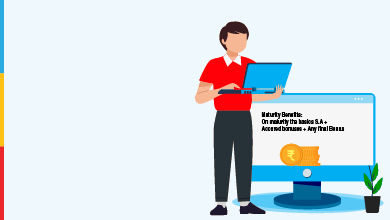
You may use the below formula to calculate the maturity benefit of your insurance plan: Maturity Benefit = Sum Assured (On Maturity) + Accrued Bonuses + Any Final Bonus

According to the recent Budget, any life insurance policies with maturity issued after April 1, 2023, and with an annual premium of more than ₹5 Lakh (apart from unit-linked insurance policies, or ULIPs) would be subject to taxation.

The nominee is not required to pay taxes on the maturity payout from a life insurance policy under Section 10(10D). As long as the premium paid does not exceed 10% of the sum assured, the maturity benefit the policyholder receives is tax-exempt.

Maturity in an insurance policy refers to the point when the policy completes its full term. If the policyholder survives till this date, the insurer pays the maturity amount. This payout may include the sum assured along with any bonuses or returns, depending on the policy type.

A guaranteed maturity benefit is a fixed amount promised by the insurer at the time of policy purchase. It is paid to the policyholder on maturity, irrespective of market performance. Such benefits are commonly offered in guaranteed income or savings insurance plans.

Pure term insurance policies do not offer any maturity benefit, as they provide only life cover. However, term plans with a return of premium option refund the total premiums paid if the policyholder survives the policy term. Standard term plans focus solely on protection, not savings.

Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover