


Proposer In Insurance

Who Is the Proposer in Insurance?

Understand the role of a proposer in insurance, how theydiffer fromthe
insured and why accurate details matter

Written by : Knowledge Centre Team

Last published : 2025-12-24

10 minutes read

Insurance is a type of contract between two parties in which one party agrees to pay the other party a sum of money in exchange for protection against a specified loss. The party paying the amount is the policyholder (or proposer), while the party receiving the premium is the insurer. Meanwhile, the insured is the person or property covered under the policy. The contract is typically between an insurance company and an individual or business. Let’s understand what the meaning of proper is and how they share a relationship with the insured with the help of this blog.

Key Takeaways

  • The proposer is responsible for selecting, applying for, and providing accurate details regarding the insurance policy

  • The proposer ensures timely premium payments to keep the policy active and avoid lapses

  • The proposer and the insured can be different individuals, such as a parent buying insurance for a child

  • The proposer can request modifications, such as updating nominee details, adding riders, or even cancelling the policy

  • A proposer’s name can be changed under specific conditions, like death, legal separation, or business transfer, subject to the insurer’s approval

Meaning of Proposer in Insurance

A proposer is an individual who applies for insurance coverage. The proposer signs the proposal form (application) and is typically responsible for paying the premiums. The proposer may propose to obtain insurance for themselves or for another person in whose life they have an insurable interest.

The simplest meaning of a proposer is the party who initiates the insurance contract by submitting a written application to the insurer. The proposer must disclose all material information about the risk being insured to the insurer, which the insurer then uses to determine whether to accept or reject the risk. If the insurer accepts the risk, it will issue a policy to the proposer.

Example: If you buy a term insurance policy for yourself,from Canara HSBC Life Insurance, you are the proposer as well as the insured, whereas Canara HSBC would be the insurer.

Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Role and Responsibilities of the Proposer in Insurance

The proposer plays a crucial role in ensuring the smooth functioning of an insurance policy. Their responsibilities extend beyond purchasing the policy to include maintaining its accuracy and validity throughout its term.

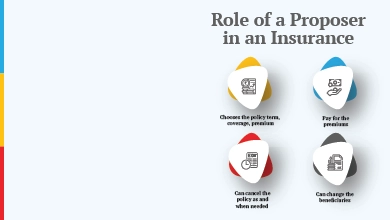
  • Contract Initiation: The proposer initiates the insurance contract by selecting a policy, submitting the necessary proposal forms, and providing required details such as age, medical history, and financial background. Their declaration forms the basis of the contract between them and the insurer.
  • Sharing and Updating of Information: A proposer must provide accurate and honest details about the insured, including their medical history, lifestyle, and financial status. Any false or withheld material information may affect policy issuance or claims. Additionally, they should update any changes in address, nominee details, or occupation during the policy term.
  • Premium Payment: The proposer is responsible for paying the insurance premium in a timely manner. If the premium is not paid within the grace period, the policy may lapse, leading to loss of coverage.
  • Policy Cancellation and Alterations: The proposer has the right to request policy modifications, such as increasing coverage, adding riders, or changing the nominee. They can also cancel the policy if needed, subject to the insurer’s terms and conditions.

Why is Proposer Important in Insurance?

A proposer is important in insurance because the insurance company uses the information provided by them to decide whether or not to provide coverage. The proposer must provide accurate information about themselves (and/or the person to be insured) and their risk factors for the insurance company to determine if they are a good candidate for coverage.

The role of the proposer in insurance is to complete and submit an insurance application (proposal form) to the insurer. The insurer will then use the information provided by the proposer to assess the risk of insuring the individual or business. If the insurer decides to offer coverage, the proposer must pay the premium.

Who Can Propose Insurance?

Any individual or business entity with an insurable interest in another person can propose that the risk be covered by an insurance company. Insurable interest implies the possibility of financial loss (or loss of support) on the unfortunate, untimely demise of the insured.

For example, if a son or daughter is the lone earning member and the parents are financially dependent on them for survival, the parent has an insurable interest in the life of their child. Similarly, a homemaker has an insurable interest in her husband’s life if he is earning. An organisation has an insurable interest in the lives of its key employees.

Do you know

Did You Know?

The term ’proposal form’ refers to a document that the proposer fills out to provide relevant risk details requested by the insurer.


Source:
IRDAI

Introducing Promise4Wealth

Is the Proposer Different From the Insured?

To understand who is a proposer in insurance, it's crucial to understand it in parallel with the insured. The proposer and the insured are usually the same person, but they can be different. The proposer is the person who signs the insurance proposal form and, therefore, the person proposing to buy the insurance. The insured is the person or people covered by the insurance policy.

The proposer pays premiums to the insurer in exchange for the insurance company's promise to pay benefits to the insured in the event of a covered loss.

Here’s a summary of the differences between the proposer and the insured if both are different persons:

Proposer in Life InsuranceInsured in Life Insurance

Proposes the insurance cover and pays the premium

Covered by the insurance

The proposer’s death does not attract a death claim on the policy unless the proposer is also the insured

The insured’s death attracts a death claim on the policy

The proposer must have an insurable interest in the insured’s life

The proposer’s death does not attract a death claim on the policy

Proposer must have a source of income

The insured does not need a source of income

The proposer will claim the tax benefits on the premium payments

The insured cannot claim tax benefits for the policy premiums (unless they pay the premiums)

The proposer is typically the policyholder and may receive maturity/survival benefits (as per policy terms)

The insured does not automatically receive maturity benefits unless they are also the policyholder/beneficiary

Proposer can be a nominee in the policy (if insurer allows; nominee is usually someone else)

An insured may be a nominee in some cases (if the proposer/policyholder is different), subject to insurer rules

Can You Change the Name of the Proposer?

Proposer is the owner of the policy. Therefore, if the proposer and the insured are different individuals, ownership can be transferred during the proposer’s lifetime through assignment/transfer as per applicable rules, but is not limited only to the death of the proposer. The proposer may also plan succession through nomination/other arrangements as per the policy and law, but a will is not the only way to enable changes.

​ Here is what you can do:

The name of the proposer can be changed in an insurance policy by contacting the insurer and requesting the change. The insurance company will then require certain documentation to process the change, such as a new application with the updated information.

A proposer is an individual who takes out a life insurance policy on another person's life. The proposer is the policyholder, and the insured is the person whose life is covered by the policy. The proposer pays the premiums and is the beneficiary of the policy only if they are named as the beneficiary/nominee, as per policy terms..

If you are a proposer, make sure you understand the different types of life insurance policies before you begin shopping for a policy. Try to understand the terms and conditions of the policy you're considering before buying it.

Conditions for Name Change

Changing the name of the proposer in an insurance policy is not an automatic process and requires adherence to specific conditions set by the insurer. The key requirements include:

  • Insurer’s Approval is Necessary: The policyholder must formally request the change, and the insurer will review the request in accordance with internal policies and regulatory guidelines.
    1. Approval depends on the reason for the proposer name in insurance change, such as the proposer’s death, business transfer, or legal separation.
    2. Some policies may impose restrictions on proposer changes; therefore, it is important to review the insurer’s terms and conditions.
  • Submission of a Formal Request with Valid Documents: The policyholder must submit a written application or fill out a proposer change request form provided by the insurer. Supporting documents may be required, including:
    1. Death certificate (in case of proposer’s demise)
    2. Legal documents (for business transfers or divorce settlements)
    3. Identity and address proof of the new proposer
    4. Relationship proof, if applicable
    5. Additional documents may be requested depending on the type of policy and the insurer’s requirements.
  • Eligibility Criteria for the New Proposer: The new proposer must meet the insurer’s eligibility criteria, including age, financial stability, and relationship with the insured.
    1. In some cases, the insurer may require a fresh risk assessment before approving the new proposer.
    2. If the new proposer does not qualify, the insurer may suggest alternative options, such as policy continuation under a different arrangement or nominee involvement.

It’s essential to consult the insurer in advance to understand the process and avoid disruptions in policy benefits.

Wrapping Up

As the primary source of information for the insurer, the proposer plays a crucial and significant role in the life insurance industry. This individual is responsible for approving and issuing the policy application. Once you realise this, obtaining life insurance is straightforward.

Glossary

  1. Proposer: The person who applies for the insurance policy, provides details and pays the premium
  2. Insurer: An IRDAI-registered company that provides the policy and covers financial risk as per the terms
  3. Insured: Person whose life is covered under the insurance policy
  4. Proposal Form: Official form submitted to the insurer containing personal, health or asset details for underwriting
  5. Nominee: Person chosen by the insured to receive benefits if a claim arises due to the death of the insured
Glossary book
Uncertain About Insurance

Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover