how-to-select-the-best-life-insurance-plan-for-working-women

How to Select the Best Life Insurance Plan for Working Women?

This guide helps working women choose the best life insurance plan by considering income, responsibilities, future goals and financial security.

Written by : Knowledge Centre Team

Last published : 2025-10-02

10 minutes read

There’s an old saying that ‘men build houses and women build homes.’ Women are the primary building block of a family unit, in other words, the builder of society. That’s why they hold immense value for the survival and growth of a family. But, often in their tight schedule of taking care of the family, they miss the opportunity to secure this value.

Women who are employed and add direct financial value to the family should be better off in this equation. But the studies point to a different picture, their participation in life insurance space, which is the basic financial need, is far lower than men.

Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Why Women Need Life Insurance?

While the reasons are many, the most prominent one is the lack of seriousness of their life cover needs. Just to give a small example, the presence of a mother in the family is as important for the children’s growth as a father.

However, when it comes to the financial value a working mother’s contribution is twofold:

  • Income adding to the family.
  • Efforts in home management.

So, the total human life value (HLV) for a working mom would be:

HLV from Income + HLV from Home Management:

A small example could be as given below:

Mother’s Human Life Value from Income.

Now, ₹ 50 lakhs is the life insurance need for women who are not earning money from outside employment. If they are, they become even more valuable to the family.

For example, if you are earning ₹ 50,000 a month your human life value would be between ₹ 60 – 90 lakhs without account for your contribution to the family.

Thus, your contribution to your family without earning money from employment is significant. If you are earning money, your presence not only contributes to the life of your family but also the lifestyle and future financial goals.

Mother’s Human Life Value for Home Management

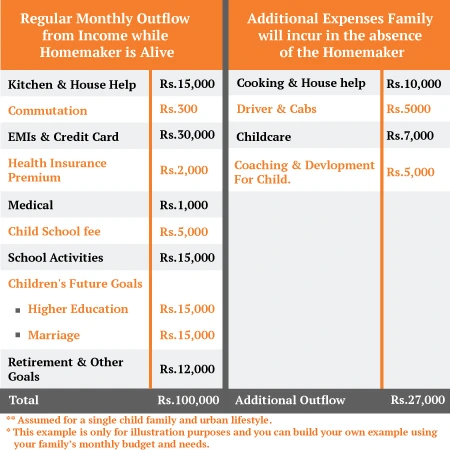
In the mother’s absence many of the household work will need to be replaced, especially childcare. But most of these replacement services will cost money:

As per this example, the mother’s human life value (life insurance need) comes out to be about ₹ 50 lakhs. If we account for you and your wife’s income and contribution in efforts, your total human life value will easily exceed ₹ 1 crore.
Buying the Best Life Insurance Policy in India

Now that you know your life insurance need (human life value) and how important it is for you; you should look for the best term insurance plan for yourself. You can look for the following factors to find the best life insurance plan for yourself and your family:


  1. Online Presence: You want to be able to buy a life insurance plan without having to run around or indulge in a lot of paperwork. The online life insurance plan will make it possible for you to securely submit your documents directly to the insurer. There are additional benefits of online life insurance plans:

    • Complete your application from anywhere in your own time.
    • Collect all the information without any pressure.
    • Discuss with family and improve your research.
    • Fill the personal information in complete privacy.

      You should understand that online presence is not a mere website for insurance products. It means the complete purchase process is online, except the medical tests. So, you can plan, estimate cost, choose your benefits and complete your application completely online.
  2. Customer Support Options: When we are talking about the presence of the entire purchase process online, it should also include the support. The insurer should also provide the product details including brochures, benefit illustrations and terms and conditions of the policy online.

    In other words, you are looking for complete transparency from the insurer. Still, you will come across information which is difficult to understand and for that customer service should help you. Here’s what you should look for in the customer service section:

    • Available contact mediums: Call, chat, e-mail.
    • vailability through the day: 24x7 or specific time.
    • Knowledge and empathy of the service agent: did he/she. understood your question and whether you are satisfied with their answer.
  3. Claim Settlement Ratio: When it’s about life insurance, how can you forget claim settlement experience? Know that the claim settlement is the real moment of truth for your life insurance plan. However, you are not likely to be a part of it, when it happens.

    So, the only thing you can do is to make sure you engage with an insurer with clear claim settlement guidelines and processes. The best online life insurance plans have claim guarantee conditions now.

    This means if your policy meets these simple conditions, the claim on your policy will be processed within a very short period; i.e. 1 – 5 working days.

    The claim settlement ratio on the other hands gives you the real picture of the insurer’s overall performance with claims. Anything above 98% is a good claim settlement record.

  4. Premium Payment Options: Premium payment options are going to be important for you, given the uncertainty that lies with career and family choices. Life insurance contracts are long-term contracts, usually extending more than a couple of decades.

    In the standard format, you’d need to pay premiums throughout the policy term. This doesn’t sound logical, especially if you see that in near future you may take a break from your career to raise children and focus on family first.

    What you need is a limited premium payment term, for example, paying the premium for a 30 years life insurance plan within just 5 – 10 years. This way your life cover doesn’t lapse if you decide to give earning a break and focus on family.

Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover



