does-your-insurance-policy-offer-these-7-benefits

Does Your Insurance Policy Offer These 7 Benefits?

Let’s learn how the right life insurance plan can support your family’s future with income, security, and long-term legacy.

Written by : Knowledge Centre Team

Last published : 2026-01-08

7 minutes read

An insurance policy acts as an umbrella on a rainy day. It is a saving tool and will provide you with peace of mind and protect your family. When it comes to purchasing a life insurance policy, there are several options available, which  means you need to do your homework and ensure that you not only get adequate coverage but also:

  • A convenient way for your family to receive the benefits

  • Safety from additional risks that may affect your earnings

  • A life cover that can do a lot more for you and your family

  • An insurance plan that evolves with your life and progress

You need to carefully analyse the benefits offered in the policy and ensure that those are present in the one you choose to buy.

A good life insurance plan should offer monthly payouts to help your family manage everyday expenses without financial stress.

Key Takeaways 

  • Choose a policy that offers monthly income to support your family’s regular needs.

  • Ensure your plan includes a premium waiver for complete protection during disability.

  • Opt for increasing life cover to match your evolving financial responsibilities.

  • Look for add-ons like child support and critical illness cover for broader safety.

  • Whole life cover helps you leave behind a lasting financial legacy.

What is a Life Insurance Policy?

Before choosing the right policy or evaluating its benefits, it is important to understand what an insurance policy is. At its core, an insurance policy is a legal contract between you and the insurer. You agree to pay regular premiums, and in return, the insurer provides a sum assured or benefit upon the occurrence of a specified event, such as death, illness, or retirement.

There are various types of insurance policies, such as term insurance, endowment plans, ULIPs, and pension plans. Each serves a different purpose, so understanding your financial goals and risk appetite is essential before making a choice.

Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

7 Must-Have Benefits in Your Life Insurance Policy

Consider the following benefits before choosing a life Insurance policy:

  • Regular Income as Policy Pay-Out: Choose a plan that not only provides a lump sum amount but also offers a regular monthly income to your family. You might ask, why monthly income?.

    Here’s a scenario that should help you understand the importance of the monthly income as a life insurance claim payout:

    Your household expenses run on a monthly budget. As long as you are present to manage the budget, your household operates smoothly. But imagine if you are not there to allocate that household budget from your income, how will your family maintain the same financial rhythm?

    You might say that the family has a large sum from the life insurance policy. Technically yes, but they not only need to run the household out of this pool, but they also need to ensure the following:

    1. They don’t end up exhausting all the money too quickly
    2. Meet all the future goals
    3. Don’t compromise too much on the lifestyle
    4. Keep tax liabilities to a minimum on the interest

These are not easy questions to answer, and even many financial and investment experts may falter at times. Plus, if you want to convert a part of the pool to ‘safe’ regular income, you need to get an annuity plan from a life insurer.

So, in a way, unless your family receives the regular income from a life insurer, they’ll need to invest a part of the pool back with the insurer. The regular payout directly as life insurance proceeds can help fill the gap and save your family unnecessary efforts.

Additionally, you can also choose an increasing monthly income instead of a fixed one, which will help the family beat inflation in the long run.
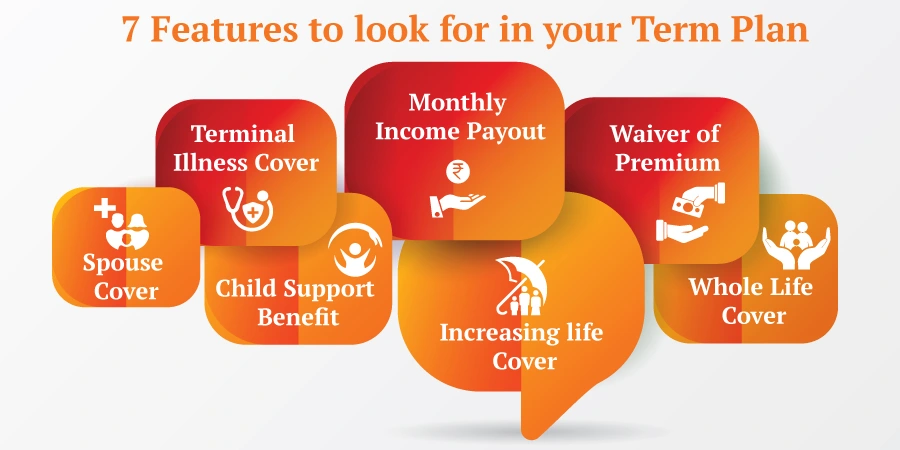
  • Premium Waiver: There are situations in life which may not be as bad as ultimate death, but they are financially devastating. For example, temporary disabilities or long-term disabilities are damaging enough to your earnings. But permanent total disabilities, like loss of both legs or hands or other limbs, can change your life forever.

    However, in that situation, you would want your life cover to continue and not compromise your family’s financial safety. The premium waiver is a feature that helps you continue the life cover in case of permanent total disability, without paying premiums.

    The iSelect Smart360 Term Plan by Canara HSBC Life Insurance offers this feature as an add-on benefit.
  • Increasing Life Cover: Unlike other needs like lifestyle and income, your life cover needs also grow, at least so far as your family and lifestyle keep growing. There are only two ways to keep your life cover adequate for your family over time:
    1. Buy a new life cover each time there’s a significant change in need
    2. Increase the life cover in your existing life insurance policy

If you have bought a term life cover previously, you know how tedious it can be to get a new policy. It is an exercise you would not like to repeat every few years. Obviously, for the second option to happen, your policy should have the feature to allow you the same. Term Insurance Plan by Canara HSBC Life Insurance offers two flexible options  to help you match your life cover with your growing needs:

  • Life-stage Increments: Life-stage increments allow you to increase your cover at crucial life moments like marriage and childbirth. Both events mark a significant increase in your financial responsibilities, giving you the chance to keep up your life cover without having to go through the entire application and underwriting process again.

    Otherwise, you can opt to increase your life cover by 5% every year. The increments will continue until the sum assured has doubled or you reach 60 years of age. This option would be more useful if you are buying term insurance when you already have a family with children.
  • Insurance Against Terminal Diseases & Disabilities: We have discussed in the second point above about disabilities which can affect your income. But disabilities are just one of the risks you can insure against; life-threatening diseases, accidental death are others.

    All three risks not only affect your income but also increase your expenses like:
    1. Treatment cost for life-threatening diseases like cancer, heart or kidney failure
    2. Hospital expenses and medical bills during recovery after an accident
    3. Modifications to life, home and vehicle after a disability

The insurance covering you and your family from these costs will help you sail through such difficult times, at least without financial worries.

  • Child Support Benefit: With all-inclusive plans like the iSelect Smart360 Term Plan by Canara HSBC Life Insurance, you don’t have to worry about your child’s future, too. Child support benefit is an added sum assured for the benefit of your child. The amount is separate from the life cover or any other benefit added to the plan. The policy pays this amount under death or critical illness claims.

    Child support benefit amount can be directly invested towards children’s goals, and it takes away another challenge of investment. Your child’s goals will be safe with this addition in place, regardless of what happens with the other benefit payouts.
  • Cover for the Homemaker: The spouse who looks after the family has immense financial value. If she goes away and can no longer look after the house and children, you will need additional support to look after growing children and their needs.

    Then why not have a life cover for her as well? Since the cover for a homemaker is based on a portion of household and other costs, it is significantly lower than your life cover. It is large enough to have either a separate term life cover or jointly with you.
  • Whole Life Cover to Leave a Legacy: The need for life cover happens to grow in the first half of your earning life, while it falls rapidly in the later stage of the second half. But unless you have opted for the return of the premium at the expiry, all the premiums go down the drain if you survive the term.

    But you can do more than just receive your premiums back at the expiry of your term life cover.

    The iSelect Smart360 Term Plan by Canara HSBC Life provides the option to receive the premiums back at 60 and continue the cover until the age of 99. Basically, it allows you to give a financial estate to your grandchildren and leave a legacy for them.

Final Thoughts

The right insurance policy can be aligned with your financial needs, and it will allow you to design your financial safety nets. Before buying the plan, consider the financial needs of your family and factor in inflation. It will ensure that your loved ones lead their life in comfort without any financial worries.

The iSelect Smart360 Term Plan by Canara HSBC Life Insurance offers all these features and more, empowering you to design a policy that matches your needs today and tomorrow. With options for higher coverage discounts and custom add-ons, it’s a plan built to keep your family’s future safe, no matter what life brings.


Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover



