building-an-emergency-corpus-using-insurance-plans

How Insurance Plans Can Support an Emergency Fund?

Learn how insurance plans can support an emergency corpus through payouts, riders and policy benefits, helping you manage sudden financial needs.

Written by : Knowledge Centre Team

Last published : 2025-08-02

11 minutes read

It’s terrible when we fall into a drastic income cut due to unexpected situations like Covid-19 and do not have an emergency corpus to take care of our contingencies. Many people have had to face hardships on the money front in this pandemic. But as they say, it is never too late. People who have missed out on building an emergency corpus could create one in the months ahead through systematic planning.

An emergency corpus is critical in uncertain times and with an emergency corpus in place, you could live worry free. Many investors get carried away by the promise of higher returns on equity and end up never building an emergency corpus for themselves. An emergency fund can be in form - from sufficient deposits in a savings account, to a unit linked insurance plan that allows pre-withdrawals in times of emergency. Ensure whatever the source be, it is accessible in a day or two to help in any crisis, should you face a sudden dip in earnings from disruptions due to a market shutdown, natural calamity etc. Such emergency corpus can help pay for major expenses like children’s education, an equated monthly installment or even usual household expenses, if needed.

How much savings would you need?

Depending on your income and regular expenses, an emergency fund can be anything between three to six months of your monthly income. If you plan to start an emergency fund now, take account of the amount of money you need for your living expenses, money payable towards school fees, EMIs payable, and other unavoidable expenses. Also, it is advised you review these every few months to monitor and incorporate any increase in expenses. You may even choose to divide your emergency fund into 2 categories, and choose saving instruments accordingly.

  • Long-Term Emergency Funds- These are long term savings plans where you save a large chunk of investments for large-scale emergencies like a sudden medical exigency or a natural disaster. This fund should be invested in plans that offer wealth creation benefits and allow you to earn considerable interests, but may also be liquid to allow emergency withdrawal. For instance, ULIP plans like Promise4Growth Plus are a great tool that lets you invest in avenues depending on your risk appetite, ensuring guaranteed results along with partial withdrawal facilities.
  • Short-Term Emergency Funds- This is the fund you must rush to in cases of smaller emergencies that may arise. These funds should allow immediate accessibility, even if the rates of interest are low. Also, these are the funds that can suffice in case of extreme situations, till you gain access to your long-term emergency funds.

Start with Making the Right Investment

Health and term insurance are a must to ensure a secure financial future for your family. In addition, unit-linked insurance policies (ULIP) that promise to pay returns at the end of the tenure are also considerable options. Apart from financial security, insurance policies are also a smart way to build wealth. While investment options such as equity and mutual funds play an important role in long-term wealth creation, there are several plans that can help fulfill both cover and savings needs.
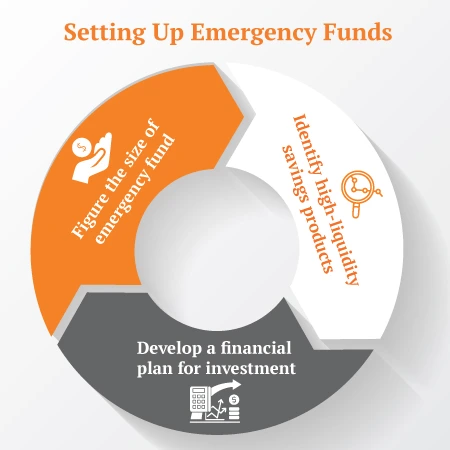

setting up emergency funds
  1. Unit Linked Insurance Plans: ULIPs combine life insurance with investment, as in the premium you pay is divided into insurance and the investment plan selected by you at the time of purchasing the policy. ULIPs let you choose from equity, debt and hybrid fund options according to your needs. Though the returns from the plan are market-linked, you have an option to switch between funds when required. Also, plans like the Promise4Growth Plus allows you to make partial withdrawal after a certain lock-in period.
  2. Endowment Plans: If you are a risk-averse, you might want to invest in endowment plans to build wealth. Endowment plans are long-term saving plans that come with life cover. The policy allows withdraw either as a lump sum amount or in monthly installments, on maturity. Also in case the insured survives the policy tenure, the lump sum amount from the policy can be used for financial objectives like children’s education, their marriage etc.

Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover




