advantages-of-buying-life-insurance-plan

Advantages of Buying Life Insurance Plan at Early Age

Start a life insurance plan early to lock in lower premiums and build long-term financial protection affordably.

Written by : Knowledge Centre Team

Last published : 2025-08-20

7 minutes read

Life insurance is generally perceived as an investment that can be considered at a much later point in life, when you've gotten older. Young investors often tend to focus on high-risk-high-reward investment options such as equities and commodities. Even conservative millennials tend to opt for investments like fixed deposits or debt mutual funds. Insurance is passed over in favour of investment options that promise quicker monetary rewards.

However, the fact remains that investing in life insurance early comes with many advantages. Once you've learned of the benefits of investing in life insurance plans early in your career, you'll understand why it should be an essential part of your retirement planning.

Key Takeaways

  • Buying life insurance in your 20s or early 30s results in significantly lower premium costs.

  • Starting early gives your money more time to grow through compounding.

  • Life insurance offers financial protection to your family when they may need it most.

  • Young buyers can choose from term plans, ULIPs, endowment, or whole life insurance, depending on their goals.

  • Common mistakes to avoid include underinsuring yourself, not comparing plans, and ignoring useful riders.

  • Early planning ensures maximum benefits at minimum cost and builds a strong foundation for financial security.

4 Reasons to Buy Life Insurance While You’re Still Young

Let’s explore why buying a life insurance policy in your 20s or early 30s might be one of the smartest financial decisions you can make.

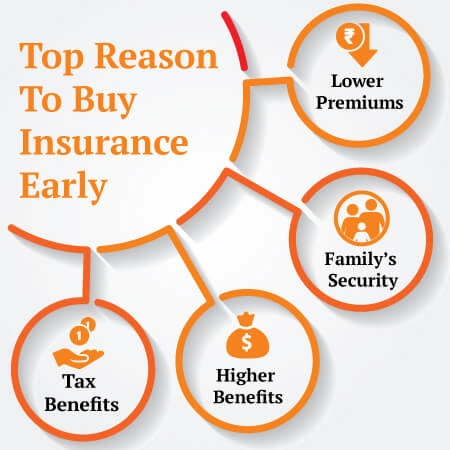
  1. You get to Pay Lower Premiums: Buying life insurance at an early age can cost you less money in the long run. Factors like age of the applicant and their general health condition are often considered by the insurer to determine the premium payable. When you're in your twenties or thirties, you tend to be in better health. This results in premium charges that are more affordable that the costs charged to older investors. Another reason life insurance plans cost less when you buy them at an early age is that your risk of dying is much less when you're younger. So, to take advantage of this provision, it's advisable to invest in life insurance early in life.
  2. Your Money Has Sufficient Time to Grow: When you buy a life insurance plan at an early age, your money has a longer time to grow. As a result, the death or maturity benefits receivable at the end of the policy's term is also greater if you invest in your twenties. For instance, if you buy a life insurance plan at 25 and continue paying premiums until you're 60, your money has 35 years to accumulate into a retirement corpus. On the other hand, if you buy the same life cover at 40, you only have 20 years to make your funds grow. Investing early can thus increase the cash value of your investment in the long run.
  3. Your Family’s Future is More Secure: In your early career years, your family may still be financially dependent on you. In the event of an unforeseen circumstance, such as your untimely passing, having a life insurance plan in place ensures that your dependents, your spouse, children, or parents, are not left financially vulnerable.

    Buying life insurance early ensures that even in the absence of wealth or large savings, your family has a financial cushion to fall back on. This peace of mind is invaluable and offers long-term emotional and financial security.
  4. You enjoy tax benefits: Aside from the advantages mentioned above, life insurance plans also offer tax benefits to the investor. Section 80C of the Income Tax Act specifies that the premium paid for life insurance during a financial year is deductible from the total income of the investor. This benefit can be claimed for premium payments up to Rs. 1.5 lakhs for each financial year. So, if your annual premium payments come up to Rs. 1 lakh, you can claim the entire amount as a deduction from your income. This, in turn, lowers your tax liability. If you buy life insurance when you're younger, you can enjoy reduced tax burden at an age when you need it most.

    Disclaimer: Tax benefits are subject to change in tax laws. Please consult your tax advisor.

Now that we have a clearer understanding of the advantages of buying life insurance early, the next step is choosing the right type of plan. Let’s break down the options best suited for young buyers.

Secure Your Family’s Future with the Right Life Insurance Plan

Please enter correct name Please enter the Full name
Please enter valid mobile number Please enter Mobile Number
Please enter valid email Please enter Email

Enter OTP

An OTP has been sent to your mobile number

Didn’t receive OTP?

Application Status

Name

Date of Birth

Plan Name

Status

Unclaimed Amount of the Policyholder as on

Name of the policy holder

Policy No.

Address of the Policyholder as per records

Unclaimed Amount

Error

Sorry ! No records Found

.  Please use this ID for all future communications regarding this concern.

Request Registered

Thank You for submitting the response, will get back with you.

Thank you for your interest in our product. Our financial expert will connect with you shortly to help you choose the best plan.

Your Family’s Future is More Secure

In your early career years, your family may still be financially dependent on you. In the event of an unforeseen circumstance, such as your untimely passing, having a life insurance plan in place ensures that your dependents, your spouse, children, or parents, are not left financially vulnerable.

Buying life insurance early ensures that even in the absence of wealth or large savings, your family has a financial cushion to fall back on. This peace of mind is invaluable and offers long-term emotional and financial security.
reason to buy insurance early

Types of Life Insurance Plans Suitable for Young Buyers

Starting early gives you the flexibility to explore various types of life insurance plans tailored to your needs, goals, and risk tolerance. Here are some standard options to consider:

  • Term Insurance: This is the most affordable and straightforward form of life insurance. It offers pure protection, meaning your nominee receives a lump sum if something happens to you during the policy term. Term plans offer high coverage at low premiums, making them ideal for young individuals looking to secure their family’s future, but they have no maturity benefit.
    Best for: Pure financial protection at the lowest cost
  • ULIPs (Unit Linked Insurance Plans): ULIPs combine life cover with market-linked investment. A portion of your premium is allocated toward insurance, while the remainder is invested in equity, debt, or balanced funds. With a long investment horizon (which you achieve by starting early), ULIPs offer the dual benefit of wealth creation and protection.
    Best for: Those who want life cover with market returns and long-term wealth-building
  • Endowment Plans: These are traditional life insurance plans that offer a mix of savings and protection. They come with a guaranteed maturity benefit and may also include bonuses. Premiums are higher compared to term plans, but they help build a disciplined savings habit over time.
    Best for: Conservative savers who want guaranteed returns along with life cover
  • Whole Life Insurance: As the name suggests, these plans provide coverage for your entire lifetime, typically up to 99 or 100 years. They also build cash value over time, which you can borrow against or withdraw. While the premiums are higher, the long-term coverage can be helpful in estate planning or legacy creation.
    Best for: Long-term protection and legacy planning

While starting early gives you a major advantage, it’s equally important to make informed decisions. Avoiding a few common mistakes can help you get the most value out of your life insurance plan.

Mistakes to Avoid While Buying Life Insurance Early

Even with all the right intentions, young buyers often overlook key aspects when purchasing their first policy. Keep these common pitfalls in mind:

  • Underinsuring Yourself: One of the biggest mistakes is opting for a cover that’s too low. Just because premiums are cheaper in your 20s doesn’t mean you should settle for the minimum. Your coverage should reflect your current lifestyle, future goals, and potential financial responsibilities. Remember, inflation will erode the value of your cover over time.
  • Buying a Plan Without Comparing Options: Life insurance is not one-size-fits-all. Don’t just buy the first policy that’s offered to you. Compare plans from different insurers, understand their benefits, features, and flexibility. A little research can lead to better coverage, lower premiums, or added features that suit your life stage.
  • Ignoring Riders and Exclusions: Riders such as accidental death benefit, critical illness coverage, or waiver of premium can significantly enhance your policy, often at a minimal additional cost. At the same time, be sure to read the fine print for exclusions, so there are no surprises during a claim.

Conclusion

Buying life insurance early in life is more than just a wise financial move; it’s a long-term commitment to your future stability and your family’s well-being. With competitive plans offered by Canara HSBC Life Insurance, you can begin investing in life insurance as early as age 18. Whether you’re single, married, or planning for retirement, there's a plan tailored to your life stage and financial goals.

So don’t wait. Secure your future today and let time work in your favour

Recent Blogs

Should I consider buying a life insurance plan if I am single?

Should You Buy a Life Insurance Plan If You are Single?

07 Aug '26
7 minute read
Find out whether buying a life insurance plan as a single individual makes sense based on financial goals, liabilities, and future responsibilities.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Life Insurance Premium Tax Deductible?

07 Aug '26
6 minute read
Learn about Tax Deduction on Life Insurance Premiums. Understand Tax Benefits Offered and Maximize Income Tax Benefits with the Right Life Insurance Plans @Canara HSBC Life Insurance.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Postal Life Insurance Scheme in India: Coverage and Benefits

07 Aug '26
7 minute read
Postal Life Insurance scheme provides high returns at low premium amounts. A smart insurance product that yield good returns. Learn who is eligible, policy types offered, key benefits, premium structure, and how it compares with private life insurance plans.
Read More
Life Insurance
Types Of Insurance Thum Desktop

Is Heart Attack Covered in Life Insurance?

06 Aug '26
6 minute read
A life insurance policy covers death due to heart attack. Insurers consider heart diseases when issuing policy. Learn why is it important to buy a life insurance plan that covers heart attack.
Read More
Life Insurance
Protect Your Dependents From Financial Liabilities Thum Mobile

How to Link Your Life Insurance Policy with DigiLocker?

06 Aug '26
7 minute read
Want quick access to your life insurance policy online? Discover how to link your policy with DigiLocker in a few simple steps for secure, paperless access.
Read More
Life Insurance
Life Insurance Payout Delays Due To Incorrect Nominee Details Thum Desktop

Easy Steps to Change Your Life Insurance Nominee Online

06 Aug '26
7 minute read
Update your life insurance nominee online instantly without paperwork. Simple, fast & hassle-free process explained.
Read More
Life Insurance
Do You Need Life Insurance If You Have No Dependents?

Life Insurance Without Dependents: Do You Really Need It?

05 Aug '26
8 minute read
Wondering if life insurance is necessary without dependents? Learn how debts, liabilities, tax planning, and future responsibilities can influence your decision.
Read More
Life Insurance
Types Of Insurance Thum Desktop

10 Super Tips to Achieve Financial Success | Financial Planning

31 July '26
6 minute read
Financial success is achievable if you follow a strategy. Learn these 10 financial planning tips and achieve financial success.
Read More
Life Insurance
Life Insurance Plans: What To Do in 2025

Life Insurance Plans: What To Do in 2026?

31 July '26
14 minute read
Reassess your life insurance in 2026 for full coverage, protection, and future security.
Read More
Life Insurance

Life Insurance - Top Selling Plans

We bring you a collection of popular Canara HSBC life insurance plans. Forget the dusty brochures and endless offline visits! Dive into the features of our top-selling online insurance plans and buy the one that meets your goals and requirements. You and your wallet will be thankful in the future as we brighten up your financial future with these plans.

Family Shield: Enhanced Protection

iSelect Smart360 Term Plan
  • 3 Plan options
  • Life cover till 99 years
  • Steady income benefit
  • Block your premium at inception

Start Young, Pay Less, Stay Secured

Young Term Plan
  • Life cover till 99 years
  • Coverage for spouse
  • Block your premium rate
  • Covers 40 critical illness

Fixed Returns, Zero Risks & Worries

iSelect Guaranteed Future Plus
  • 4 Plan options
  • Life cover + Guaranteed benefits
  • Accidental death benefit
  • Premium protection cover




